ENGLISH EDITION · 議題探討
The Structural Separation: Why Carbon Accounting Is Separating Physical Reality from Market Claims
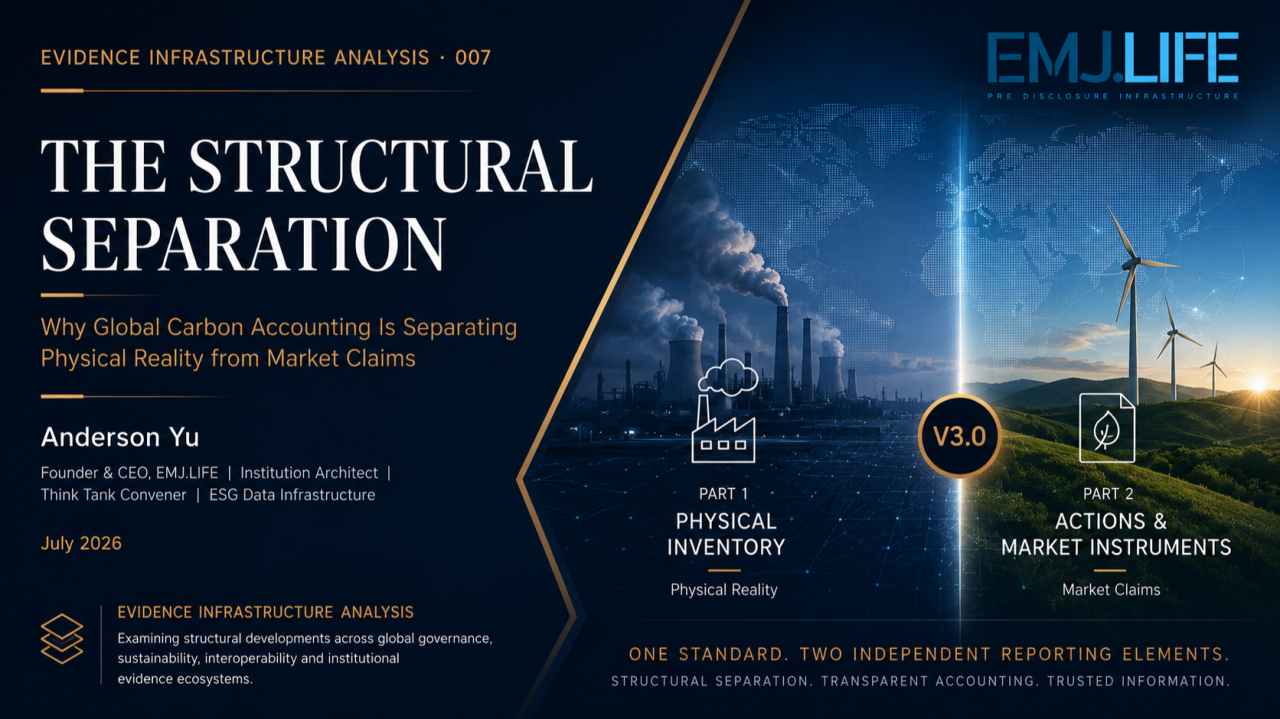
The GHG Protocol's 2026 development plan separates physical inventories from market actions, requiring carbon information to remain distinguishable and traceable from its operational origin.
This English edition is available for independent reading and search discovery.
Executive Summary / Lead
The GHG Protocol's 2026 development plan proposes a multi-part Corporate Standard in which physical inventories and actions or market instruments become separately governed reporting elements. The key signal in the GHG Protocol development direction is not merely a revision of the Corporate Standard. It is that distinct carbon information should not be combined too early. A physical emissions inventory describes emissions arising from operations and value chains. Contracts, certificates, offsets and other market actions describe acquired attributes or claims. They may jointly inform decisions, but they are not the same evidence type. This Analysis therefore does not treat the structural separation of physical emissions inventories and market claims as a self-contained technical or policy update. It separates the institutional facts supported by the official anchor, SNN editorial inference and outcomes that remain unverified. The reader should be able to see where the source ends, where interpretation begins and which conclusions the present evidence cannot support. To make the lead decision-ready, it answers five questions together: what has occurred, which first-party record supports it, through what mechanism the effect may travel, which outcome evidence is still missing, and what next observation could strengthen or overturn the judgement. Any causal relationship not stated by the source remains an editorial inference and is not converted into a factual claim through confident wording.
Company & Industry Context
For more than two decades, physical emissions, certificates and contractual claims used different methods but entered a shared inventory architecture. The new direction requires distinct categories of carbon information to remain institutionally separated. Reporting processes have often distinguished location-based, market-based and offset claims only in the final inventory, while upstream systems retain a single energy or carbon dataset. When physical activity, contractual rights and communication claims share fields without separate identities, the organisation cannot reliably tell whether a number represents physical emissions, an accounting adjustment or a market attribute. Institutional context must identify the rule setter, implementer, data owner, reviewer and affected market. Those roles may sit in different organisations or functions, and publication of a document, deployment of a system, enterprise adoption and delivery of an outcome are different evidence states. Time and authority must also be separated. An announcement date is not an effective date; a pilot is not general adoption; a technical specification is not a legal obligation; and voluntary enterprise use is not regulatory approval. Putting these events on one timeline shows when an institutional development actually enters data, contract, investment or disclosure processes and which actor is authorised to make that transition.
Challenge / Why It Matters
If separation happens only at reporting time, double counting, provenance confusion and unclear claim boundaries become more likely. The difficult task is preserving intended use and attribution when operational data is first created. Structural separation addresses double counting and misplaced responsibility, not only format. One renewable certificate may be referenced by multiple entities, a reduction activity may enter both an inventory and an additional claim, and a contract period may not align with the period of energy use. If reconciliation occurs manually at the reporting endpoint, the error may already have spread into supply-chain, finance or product claims. When upstream evidence lacks stable identity, formation time, applicable boundary and version, a standardised output may still be impossible to reconstruct. The material risk is not one missing field. It is the silent conversion of the wrong entity, an expired method, an inferred relationship or an unapproved version into an apparent fact as information moves downstream. Concrete failure modes include incorrect entity matching, an incomplete data population, inconsistent boundaries, unversioned methods or factors, exceptions without rationale, approval occurring after publication, and downstream reuse outside the original purpose. Each failure can turn a reasonable individual record into a conclusion that cannot be defended after aggregation, comparison or machine-assisted interpretation.
Action / Solution / Implementation
Companies need separate data paths, identifiers, verification rules and version controls for physical emissions, reduction actions and market instruments, while maintaining explainable relationships among them. Companies should maintain separate data paths for fuel and electricity activity, emissions factors, primary supplier data, contracts, certificates, offsets, retirement, claims and reporting versions. Every market instrument needs a unique identity, rights holder, period, geography, retirement status and permitted statement. Explicit rules then explain its relationship to the physical inventory without rewriting the underlying activity record. The implementable control unit is a governed evidence object. Each material claim links to its primary source, calculation or judgement method, organisational and temporal boundary, accountable owner, control state, exception, approval and version. When any component changes, the system preserves the difference and affected uses instead of overwriting the earlier basis. A minimum operating control set includes a claim register, evidence owner, source snapshot, method identity, valid period, control frequency, exception threshold, review, approval and permitted downstream use. High-judgement or high-financial-impact items receive a stronger review tier. Lower-risk records use automated completeness and consistency checks so that governance effort is concentrated where a wrong claim would change a decision.
Evidence / Results / Impact
The plan outlines a multi-part Corporate Standard 3.0 and a path toward joint publication with ISO. Scope 3 work also considers stronger primary-data expectations and data-quality hierarchies. Official GHG Protocol materials support the standards architecture and development process, while options, timing and final requirements under consideration must be checked against formal decisions. This Analysis treats separation as an institutional direction. It does not claim that market instruments are inherently invalid or that one location-based or market-based result is the sole truth; the requirement is to preserve how each result was formed. Evidence assessment begins with the official anchor and uses independent primary or method-transparent sources to test context and limits. The sources support stated institutional facts and explicit figures. Claims of comprehensive adoption, causal improvement or universal cross-market effectiveness require separate implementation evidence. Every material sentence should enter a claim ledger and be classified as official fact, direct measurement, estimate, corporate commitment, delivered outcome or SNN editorial inference. The ledger records the precise scope that each source supports. Conflicting evidence is retained with the resolution rationale; absent evidence is marked pending rather than filled with a convenient analogue from another entity, period or jurisdiction.
Industry & Institutional Implications
Carbon accounting will move from calculation accuracy alone toward information architecture integrity. Assurance and oversight will need to test that distinct reporting elements were not blended during the process. For boards, investors and assurance providers, separated information answers three questions more clearly: what operations physically emitted, what actions the company took, and which instruments support which claims. That improves explainability and also exposes period mismatch, overlapping rights and methodological change previously hidden inside an aggregate number. The purpose of this information density is not length for its own sake. It is to shorten the verification distance between claim and decision. Boards, investors, regulators and operational teams should be able to distinguish fact, estimate, commitment, progress and outcome, then update the judgement when conditions change without reconstructing the case from scattered files and oral explanation. Accountability therefore attaches to decision rights. The data owner maintains the source, the method owner controls calculation, the business function defines the use case, internal control or assurance tests reproducibility, and the approver accepts responsibility for final use. An exception without an expiry date, remediation owner and impact scope stops being temporary treatment and becomes persistent evidence debt.
SNN Editorial / Pre-Disclosure Evidence Infrastructure Perspective
SNN editorial analysis: The global GHG Protocol direction separating physical emissions from market claims directly affects Taiwan semiconductor, electronics, steel and brand exporters serving European customers. Companies must separately preserve inventories, power contracts, certificates, offsets, periods and claim boundaries to prevent double counting and support assurance reconstruction. Taiwan semiconductor, electronics, steel and brand exporters use grid factors, renewable transfers, power-purchase agreements, certificates and supplier data. For European customers, IFRS S2 or product-carbon requirements, physical energy use and market instruments must remain independently recorded, with distinct organisational, product and claim boundaries. Otherwise the same renewable or reduction outcome may be reused across companies, products and periods. For Taiwan, relevance should be traced through an actual transmission path. An international rule or customer requirement first enters finance, procurement, contract, supplier-data and assurance processes, then changes local systems and controls. It does not automatically become Taiwan law. Companies need to identify the applicable scenario, preserve bilingual mappings and make the evidence chain reviewable under controlled access. Taiwan companies can perform the transmission test on concrete objects: the company and legal entity, facility, product, batch, supplier, contract, financing instrument and disclosure field. Chinese and English names, internal and external classifications and different reporting frameworks should resolve to the same claim identity. Traceability must still preserve commercial confidentiality, personal data and access boundaries; it does not require unrestricted publication.
Future Outlook
Review should follow the final standard, ISO collaboration, Scope 3 decisions and market-instrument accounting. Editors must not present options in the development plan as requirements already in force. Future evidence should follow Corporate Standard 3.0, Scope 2 and Scope 3 technical decisions and ISO collaboration. A low-regret action is to select one energy or market instrument and build dual data lineage from source activity to final claim, testing whether a user can confirm rights, retirement, period and reporting use without changing the physical inventory. Future monitoring should separate final text, technical guidance, adoption scope, operating controls, supervision and observable outcomes. A low-regret step is to select one high-risk claim for an end-to-end reconstruction test and record missing identity, source, method, accountability and version. That is governance preparation, not a compliance guarantee or forecast of results. Monitoring should be event-triggered as well as calendar-based. A final rule, amended technical guidance, expanded scope, supervisory action, adoption data or observed outcome creates a new version and a reassessment of the earlier judgement. The prior conclusion is not erased. It retains its original basis, identifies the new evidence that changed it and states which decisions or downstream uses now require review.
Sources, evidence chain and editorial responsibility
Source publication: sustainabilitynewsnetwork.net · Original author: Anderson Yu · Original publication date:
Original publication
External institutional and reporting sources
These external announcements, rules, studies and reports support the discussion and are displayed separately from the original publication.
- Primary analysis sourceGHG ProtocolGHG Protocol Corporate Standard ↗Published date not provided · Accessed 2026-08-16 19:26:49
Official primary source selected through publication-level web research.
- Taiwan market-context source行政院國家永續發展委員會我國碳定價制度關鍵里程碑 企業申報碳費總額達49.7億元 ↗Published 2026-06-03 · Accessed 2026-08-25
Supports the Taiwan operational carbon-data context across semiconductor, power, chemicals, steel, cement and electronics industries.
Topic hub: Pre-Disclosure Evidence Infrastructure