議題探討
下一項永續能力是制度能力
全球永續工作正從增加報導要求,轉向建立可信揭露之前所需的營運、治理、決策與證據能力。
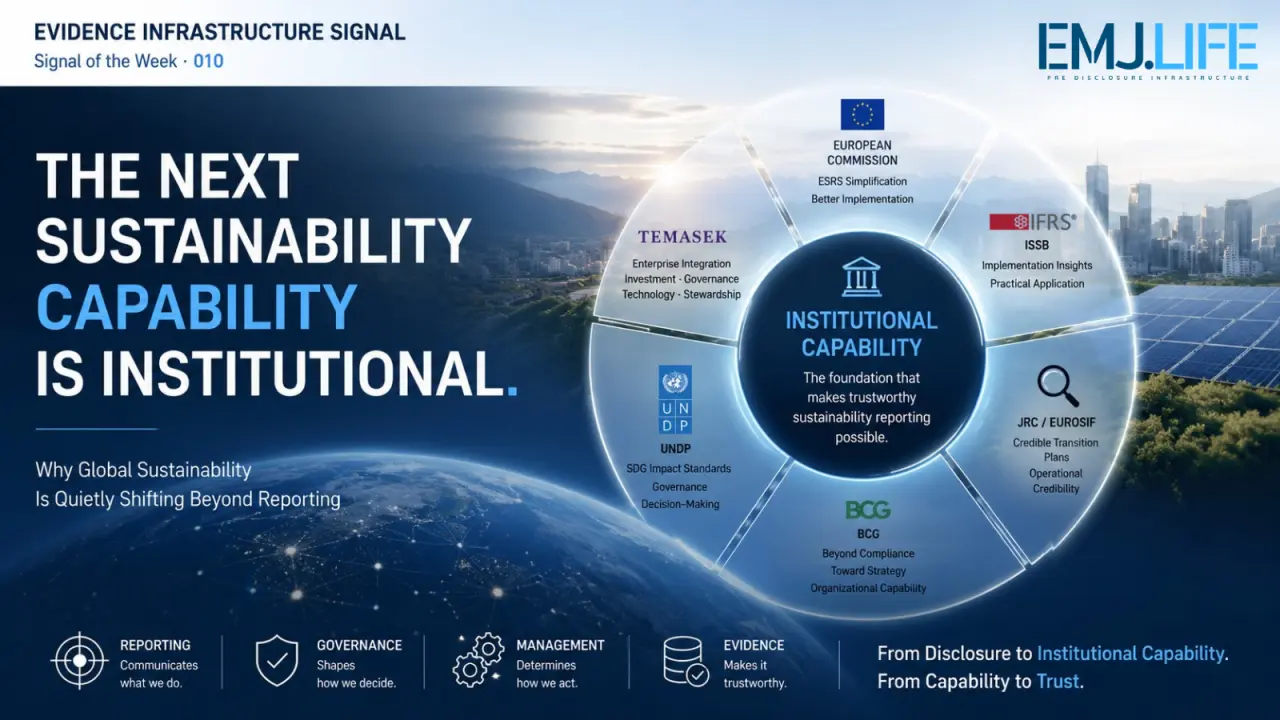
The Next Sustainability Capability Is Institutional.
Why Global Sustainability Is Quietly Shifting Beyond Reporting
重點摘要
Executive Summary / Lead近期全球永續發展顯示,下一項競爭力不只是會報導,而是組織能否在揭露之前持續產生可靠、結構化與決策有用的證據。 本期共同訊號是,全球永續工作正在從增加揭露要求,轉向企業是否具備持續執行要求的制度能力。報導簡化、轉型計畫、治理標準與策略整合看似不同,卻都暴露同一點:缺少責任、控制、營運證據與決策連結,組織就無法穩定產生可信揭露。 本期 Signal 將 可信揭露之前的制度能力成為下一項競爭力 視為多個制度行動逐步收斂的方向,而不是任何一個機構已宣布的共同計畫。各訊號的法律地位、發布時間與適用對象仍須分列,交叉閱讀只能支持方向判斷,不能把相似語言改寫成統一義務。 為使摘要能直接支援決策,本段同時回答五個問題:已發生什麼、由哪一第一方紀錄支持、影響透過什麼機制傳導、目前仍缺少哪些結果證據,以及下一個可推翻或強化判斷的檢查點。任何未被來源明示的因果關係都保留為編輯推論,不以肯定語氣包裝。
Recent developments suggest that the next sustainability capability is not reporting alone, but the ability to generate reliable, structured and decision-useful evidence before disclosure. The common signal is that global sustainability work is moving from additional disclosure requirements to whether an enterprise has the institutional capability to execute requirements continuously. Reporting simplification, transition plans, governance standards and strategy integration appear different, yet all reveal the same condition: without responsibility, controls, operational evidence and decision links, credible disclosure cannot be produced reliably. This Signal treats institutional capability before credible disclosure as the next competitive advantage as a direction emerging across institutional actions, not as a joint programme announced by any one authority. Legal status, publication date and population remain source-specific. Cross-reading supports a directional judgement only; similar language must not be converted into a single obligation. To make the lead decision-ready, it answers five questions together: what has occurred, which first-party record supports it, through what mechanism the effect may travel, which outcome evidence is still missing, and what next observation could strengthen or overturn the judgement. Any causal relationship not stated by the source remains an editorial inference and is not converted into a factual claim through confident wording.
企業與產業背景
Company & Industry Context歐盟修訂 ESRS、ISSB 實作內容、歐盟聯合研究中心轉型計畫調查、BCG 策略觀點、UNDP SDG Impact Standards 與 Temasek 實務各自處理不同制度環節。 制度能力不是一個永續部門的技能,而是跨財務、營運、採購、法務、資訊、內控與董事會的協作結構。資料形成必須有擁有人,方法必須有核准,例外必須被處理,決策必須留下依據;否則報導仍依賴少數人在期末人工整合。 訊號收斂的判斷基礎不是關鍵字相似,而是不同制度是否開始要求相近的資料身分、來源、方法、責任、控制與版本能力。每筆來源仍保留自己的治理權限與時間點,避免把跨機構比較誤讀成制度合併。 時間與權限也必須分開記錄:公告日不等於生效日,試點不等於普遍採用,技術規格不等於法律義務,企業自願導入也不等於監理核准。把這些節點放在同一時間軸,才能判斷一項制度變動何時真正進入資料、合約、投資或揭露流程。
Revised ESRS, ISSB implementation work, the JRC transition-plan survey, BCG strategy analysis, UNDP SDG Impact Standards and Temasek practice address different institutional layers. Institutional capability is not a sustainability-team skill. It is a structure connecting finance, operations, procurement, legal, IT, internal control and the board. Data need owners, methods need approval, exceptions need treatment and decisions need retained reasons. Otherwise reporting remains a year-end integration exercise performed by a small number of people. Convergence is not established by repeated vocabulary. It is established when independent institutions begin to require comparable capabilities around identity, origin, method, accountability, control and version. Every source retains its own authority and time reference so that comparison does not become a claim of institutional merger. Time and authority must also be separated. An announcement date is not an effective date; a pilot is not general adoption; a technical specification is not a legal obligation; and voluntary enterprise use is not regulatory approval. Putting these events on one timeline shows when an institutional development actually enters data, contract, investment or disclosure processes and which actor is authorised to make that transition.
挑戰與重要性
Challenge / Why It Matters簡化報導不會自動創造實作能力,發布轉型計畫也不會自動產生可信度。治理、營運與決策若沒有可靠證據,報導品質仍受限制。 簡化規則可能降低填報量,卻不會自動修復底層資料。企業也可能發布完整轉型計畫,但資本預算、供應商與績效責任沒有跟進。當市場把較少欄位誤認為較低能力要求,組織會延後投資,直到客戶、銀行或確信程序要求原始證據才暴露缺口。 上游證據若沒有穩定識別、形成時間、適用邊界與版本,最終輸出即使格式一致,覆核者仍可能無法重建形成過程。真正風險不是單一欄位缺失,而是錯誤主體、過期方法、推定關係或未核准版本在傳遞中被當成確定事實。 具體失效模式至少包括主體配對錯誤、資料人口不完整、邊界前後不一致、方法或係數未版本化、例外未留下理由、核准與發布時間倒置,以及下游重用時脫離原用途。每一種失效都可能讓合理的單筆資料,在彙總後形成無法防禦的結論。
Simpler reporting does not create implementation capability, and publishing a transition plan does not create credibility. Governance and operations still require reliable evidence. Simplified rules can reduce reporting volume but do not repair source data. A company can also publish a complete transition plan while capital budget, suppliers and performance responsibilities do not follow. When fewer fields are mistaken for lower capability requirements, investment is delayed until a customer, bank or assurance process asks for primary evidence. When upstream evidence lacks stable identity, formation time, applicable boundary and version, a standardised output may still be impossible to reconstruct. The material risk is not one missing field. It is the silent conversion of the wrong entity, an expired method, an inferred relationship or an unapproved version into an apparent fact as information moves downstream. Concrete failure modes include incorrect entity matching, an incomplete data population, inconsistent boundaries, unversioned methods or factors, exceptions without rationale, approval occurring after publication, and downstream reuse outside the original purpose. Each failure can turn a reasonable individual record into a conclusion that cannot be defended after aggregation, comparison or machine-assisted interpretation.
行動、方案與執行
Action / Solution / Implementation組織需把資料形成、控制、責任、決策連結與證據保存嵌入日常營運,使可信揭露成為制度能力的結果。 制度能力可被分解為穩定身分、資料責任、方法治理、內部控制、版本管理、跨部門決策、外部證據與矯正回饋。每項能力要有可觀察紀錄與責任人,而不是政策聲明;揭露只是這些日常能力在特定期間的受控輸出。 可執行的控制單位應是受治理的證據物件:每項重要主張連接原始來源、計算或判斷方法、組織與時間邊界、責任人、控制狀態、例外、核准及版本。當任何元件改變時,系統保存差異與影響範圍,不以覆寫舊檔取代變更紀錄。 營運上可建立最小控制集:主張登錄、證據擁有人、來源快照、方法識別、適用期間、控制頻率、例外門檻、覆核與核准,以及允許的下游用途。高判斷或高財務影響項目採更嚴格的覆核層級;低風險資料則以自動化完整性檢查降低重工。
Organizations need evidence formation, controls, responsibility, decision links and preservation embedded in everyday operations so trustworthy disclosure becomes an outcome. Institutional capability can be decomposed into stable identity, data ownership, method governance, internal control, version management, cross-functional decision, external evidence and corrective feedback. Each capability needs an observable record and accountable owner, not a policy statement. Disclosure is the controlled output of those daily capabilities for a period. The implementable control unit is a governed evidence object. Each material claim links to its primary source, calculation or judgement method, organisational and temporal boundary, accountable owner, control state, exception, approval and version. When any component changes, the system preserves the difference and affected uses instead of overwriting the earlier basis. A minimum operating control set includes a claim register, evidence owner, source snapshot, method identity, valid period, control frequency, exception threshold, review, approval and permitted downstream use. High-judgement or high-financial-impact items receive a stronger review tier. Lower-risk records use automated completeness and consistency checks so that governance effort is concentrated where a wrong claim would change a decision.
證據、成果與影響
Evidence / Results / Impact本期從 2026 年 7 月多個國際機構的出版與政策進展,辨識出報導簡化、實作優先、營運可信度與策略整合的共同方向。 本期來源能支持多個機構對實作、策略與治理的關注,但不能證明市場已形成單一成熟度模型。SNN 所稱 institutional capability 是跨出版的結構判讀,不是新的評級、認證或對特定企業能力作出的結論。 證據判讀採來源對照而非票數累加。多筆文件若都引用同一基礎資料,仍只構成一條證據路徑;不同機構出現相近要求,則可提高方向性訊號,但不能證明執行成效、法律等同性或所有市場已同步成熟。 每一項關鍵句都應進入 claim ledger,標示其為官方事實、直接量測、估算、企業承諾、已交付結果或 SNN 編輯推論,並記錄來源所能支持的精確範圍。若兩筆來源衝突,保留衝突與處理理由;若資料尚未出現,明確標成待驗證,而不是以相近案例補成確定答案。
The edition identifies a shared direction across July 2026 developments: reporting simplification, implementation priority, operational credibility and strategic integration. The sources support increased institutional attention to implementation, strategy and governance, but do not establish one market-wide maturity model. SNN's institutional capability is a structural inference across publications, not a new rating, certification or conclusion about the capability of a named company. Evidence is assessed through source comparison rather than a simple source count. Documents that repeat one underlying dataset remain one evidential path. Similar requirements from independent institutions can strengthen a directional signal, but they do not prove implementation results, legal equivalence or equal market maturity. Every material sentence should enter a claim ledger and be classified as official fact, direct measurement, estimate, corporate commitment, delivered outcome or SNN editorial inference. The ledger records the precise scope that each source supports. Conflicting evidence is retained with the resolution rationale; absent evidence is marked pending rather than filled with a convenient analogue from another entity, period or jurisdiction.
產業與制度意涵
Industry & Institutional Implications永續成熟度的衡量可能從報表數量,轉向組織能否穩定執行要求並產生可被信賴的依據。 競爭優勢來自企業能以較低重工成本回應新要求,並在方法或政策改變時快速辨識受影響證據。具制度能力的組織可以解釋決策與限制;只具報導能力的組織則可能每次重新蒐集,在時間壓力下接受更高估算與確信風險。 這種資訊密度的目的不是增加篇幅,而是縮短主張到決策之間的查核距離。董事會、投資人、監理者與營運團隊應能辨識哪些內容是事實、估算、承諾、進度或結果,並在情境改變時更新判斷,而不是重新尋找散落的檔案與口頭說明。 責任分工因此必須落到決策權:資料擁有人維護來源,方法擁有人控制計算,業務單位說明使用情境,內控或確信人員測試可重建性,核准者承擔最終採用責任。例外若沒有到期日、補救人與影響範圍,就會從暫時處置變成永久的證據債務。
Sustainability maturity may be measured less by reporting volume and more by the ability to implement requirements consistently and produce a trustworthy basis. Competitive advantage arises when a company responds to new requirements with less rework and rapidly identifies evidence affected by a method or policy change. An institutionally capable organisation can explain decisions and limitations. A reporting-capable organisation recollects data each time and accepts higher estimation and assurance risk under deadline. The purpose of this information density is not length for its own sake. It is to shorten the verification distance between claim and decision. Boards, investors, regulators and operational teams should be able to distinguish fact, estimate, commitment, progress and outcome, then update the judgement when conditions change without reconstructing the case from scattered files and oral explanation. Accountability therefore attaches to decision rights. The data owner maintains the source, the method owner controls calculation, the business function defines the use case, internal control or assurance tests reproducibility, and the approver accepts responsibility for final use. An exception without an expiry date, remediation owner and impact scope stops being temporary treatment and becomes persistent evidence debt.
SNN 編輯與揭露前證據基礎設施觀點
SNN Editorial / Pre-Disclosure Evidence Infrastructure PerspectiveSNN 編輯分析:歐洲與全球制度更新對台灣企業的真正考驗,是揭露前是否已有資料責任人、內部控制、供應商證據與覆核機制。大型上市公司與中小出口商若等到報告期才因應,三個月資訊落差就會轉成接單與融資風險;制度能力必須成為日常營運的一部分。 台灣首批 IFRS 永續揭露公司、中小出口商與金融機構面對歐洲客戶及全球資本時,真正準備不是購買新模板,而是把資料責任、供應商證據、內控與管理決策嵌入日常。大型企業還要讓要求傳到供應鏈時具備比例原則,避免把制度負擔直接轉嫁給無能力的小型供應商。 對台灣市場的意義應沿實際傳導路徑判斷:國際制度或客戶要求先進入融資、採購、合約、供應商資料與確信流程,再影響台灣企業的系統與控制。這不等於外國規則自動成為台灣法律義務;本地企業要做的是辨識適用情境、保留跨語言對應並建立可授權覆核的證據鏈。 台灣企業可把傳導測試落在具體物件:公司與法律主體、廠區、產品、批次、供應商、合約、融資工具及揭露欄位。中英文名稱、內外部分類與不同框架之間應連到同一主張識別,同時保留商業機密、個資與權限邊界,避免可追溯被誤解為全面公開。
SNN editorial analysis: The real test created by European and global updates is whether Taiwan enterprises already have data owners, internal controls, supplier evidence and review mechanisms before disclosure. If listed companies and SME exporters wait for reporting season, a three-month information lag becomes an order and financing risk. Taiwan first-wave IFRS sustainability reporters, smaller exporters and financial institutions facing European customers and global capital need more than new templates. Data ownership, supplier evidence, controls and management decisions must enter daily work. Larger companies should also apply proportionality when requirements reach supply chains instead of transferring institutional burden to smaller suppliers without capability. For Taiwan, relevance should be traced through an actual transmission path. An international rule or customer requirement first enters finance, procurement, contract, supplier-data and assurance processes, then changes local systems and controls. It does not automatically become Taiwan law. Companies need to identify the applicable scenario, preserve bilingual mappings and make the evidence chain reviewable under controlled access. Taiwan companies can perform the transmission test on concrete objects: the company and legal entity, facility, product, batch, supplier, contract, financing instrument and disclosure field. Chinese and English names, internal and external classifications and different reporting frameworks should resolve to the same claim identity. Traceability must still preserve commercial confidentiality, personal data and access boundaries; it does not require unrestricted publication.
未來展望
Future Outlook未來應觀察企業是否建立可重複的責任、控制、營運證據與治理決策鏈,而非只更新揭露模板。 後續應觀察企業是否以實際能力而非報告數量衡量成熟度。低後悔行動是對一項重大揭露進行 capability walkthrough,逐步確認來源、責任、方法、控制、核准與矯正,記錄任何只能靠特定人員記憶完成的節點並制度化。 後續追蹤應分開最終文件、技術指引、採用範圍、執行控制、監督活動與可觀察結果。現階段的低後悔行動,是挑選一項高風險主張做端到端重建測試,記錄缺少的身分、來源、方法、責任與版本;這是治理準備,不是合規保證或結果預測。 監測不只依日曆,而應由事件觸發:最終規則發布、技術指引變更、適用範圍擴大、主管機關執法、企業採用數據或實際成果出現時,都建立新版本並重評原判斷。舊結論不刪除,而是標示當時依據、被何種新證據修正,以及哪些決策需要重新檢視。
Future assessment should focus on repeatable responsibility, controls, operational evidence and governance decision chains rather than template updates alone. Future assessment should examine whether companies measure maturity through real capability rather than report count. A low-regret action is a capability walkthrough of one material disclosure, confirming source, owner, method, control, approval and remediation and institutionalising every step that currently depends on one person's memory. Future monitoring should separate final text, technical guidance, adoption scope, operating controls, supervision and observable outcomes. A low-regret step is to select one high-risk claim for an end-to-end reconstruction test and record missing identity, source, method, accountability and version. That is governance preparation, not a compliance guarantee or forecast of results. Monitoring should be event-triggered as well as calendar-based. A final rule, amended technical guidance, expanded scope, supervisory action, adoption data or observed outcome creates a new version and a reassessment of the earlier judgement. The prior conclusion is not erased. It retains its original basis, identifies the new evidence that changed it and states which decisions or downstream uses now require review.
來源、證據鏈與責任編輯
來源媒體:sustainabilitynewsnetwork.net · 原文作者:Anderson Yu · 原文發布:
原始出版
外部論述與制度來源
以下外部公告、法規、研究或新聞用於支撐本文論述,並與原始出版分開呈現。
- Primary analysis sourceUNDP SDG ImpactSDG Impact Standards for Enterprises ↗出版日期 日期未標示 · 查核時間 2026-08-17 03:26 (UTC+8)
Official primary source selected through publication-level web research.
- Taiwan market-context source臺灣證券交易所ESG生態系專區上線 引領永續新價值 ↗出版日期 2026-03-23 · 查核時間 2026-08-25(時間未記錄)
Supports Taiwan implementation across digital filing, formatted sustainability information, assurance, ESG evaluation and AI-assisted review.