永續學堂
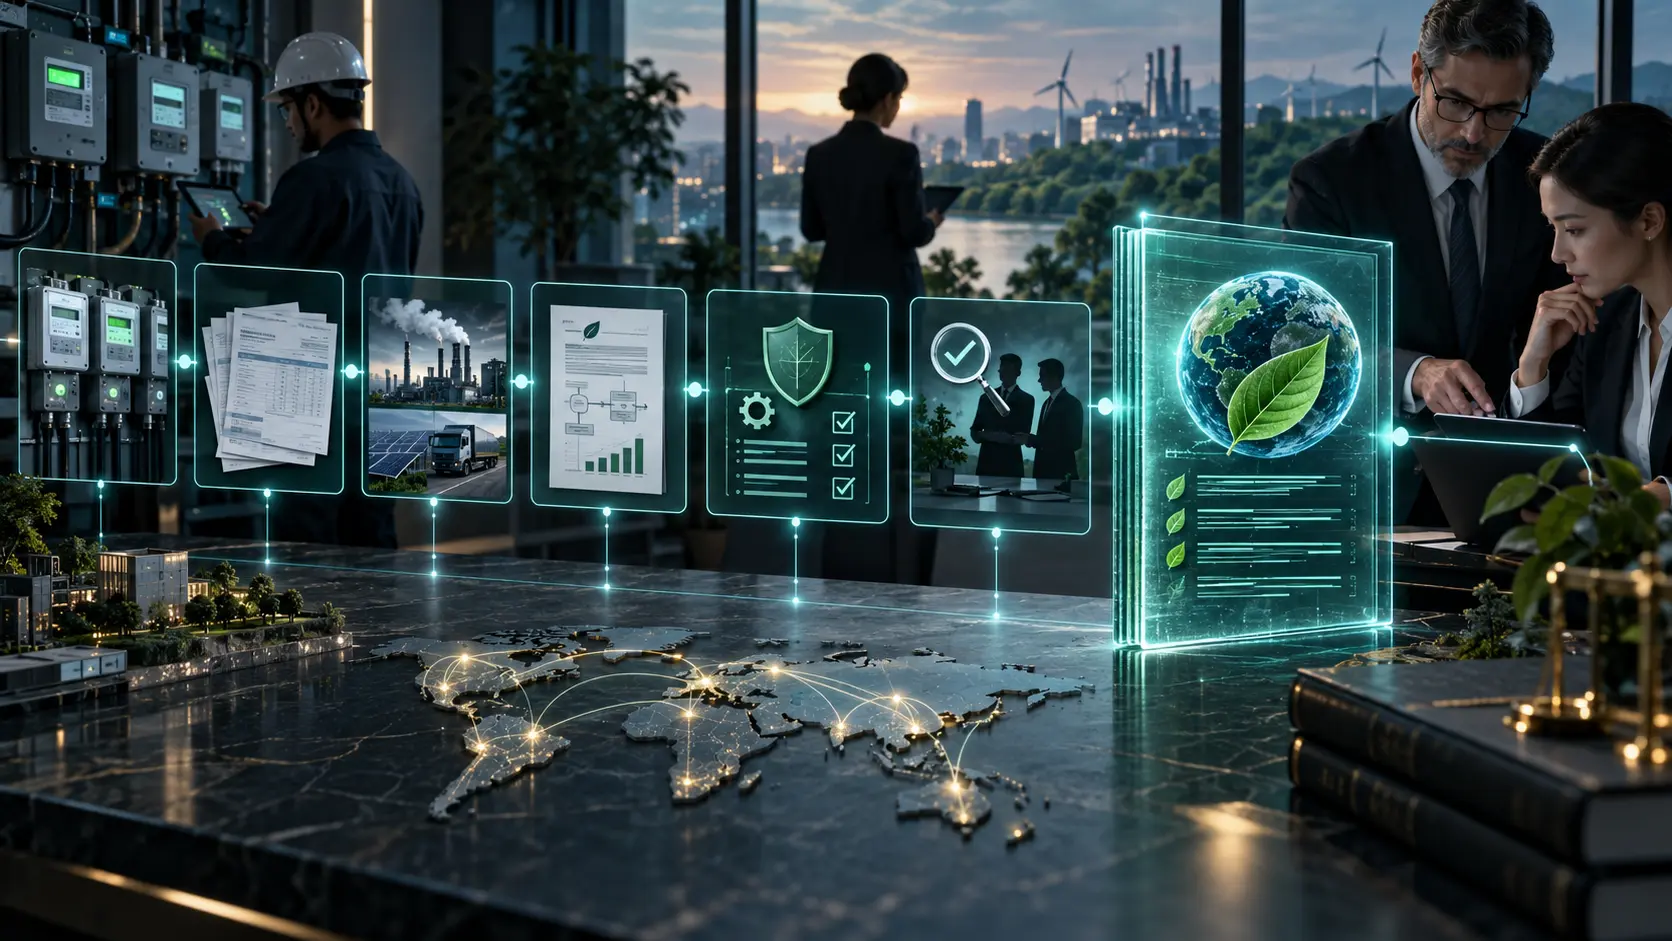
企業溫室氣體盤查如何做到可查核,從原始憑證、方法鎖版到範疇 3 安全港
SNN.TW 編輯報導SNN.TW Editorial Reporting
ESG Today 專文整理企業建立可查核溫室氣體盤查的資料、控制與確信要點,並以加州 SB 253 時程說明範疇 1、2、3 及安全港安排。
How Companies Can Build an Audit-Ready GHG Inventory From Source Evidence to Method Control
An ESG Today guest article outlines data, control and assurance practices for an audit-ready greenhouse-gas inventory and uses California SB 253 timelines to explain Scope 1, 2 and 3 reporting and safe-harbour treatment.
重點摘要
Executive Summary / LeadESG Today 在本次掃描區間發布或實質更新此事件。專文說明企業需從活動數據、排放係數、組織邊界、估計與控制紀錄建立盤查,並提及加州 SB 253 對大型企業範疇 1、2 與後續範疇 3 的申報及確信節點。
ESG Today published or materially updated this event within the verified scan window. The article explains how activity data, emissions factors, organisational boundaries, estimates and controls form an inventory, and describes California SB 253 reporting and assurance milestones for large companies across Scope 1, 2 and later Scope 3.
企業與產業背景
Company & Industry Context可查核盤查不是單一試算表,而是從來源憑證到最終揭露的資料供應鏈。 本稿以來源可核對的事件、數字與主體重寫,不沿用來源文章段落結構。
An audit-ready inventory is not one spreadsheet but a data supply chain from source evidence to final disclosure. This SNN draft rewrites only source-supported events, figures and entities without reproducing the source article's paragraph structure.
挑戰與重要性
Challenge / Why It Matters組織邊界、係數版本、缺值估計與供應商資料若未留痕,查核時無法重演。 重要性在於承諾、資本配置或政策分類若缺少清楚邊界,可能被市場誤讀為已完成成果。
Assurance cannot reproduce an inventory when organisational boundaries, factor versions, missing-data estimates and supplier evidence are not retained. The central issue is that a commitment, capital allocation or policy label can be mistaken for a completed outcome when its boundary is unclear.
行動、方案與執行
Action / Solution / Implementation企業應建立資料字典、責任矩陣、計算鎖版、變更紀錄、抽樣與管理覆核。 執行時應保存適用範圍、責任人、方法版本、核准節點與例外處理,使後續來源審查可以重現判斷。
Companies should establish a data dictionary, responsibility matrix, locked calculations, change logs, sampling and management review. Implementation should preserve scope, accountable owner, method version, approval checkpoints and exception handling so a later Source Review can reproduce the decision.
證據、成果與影響
Evidence / Results / Impact法規時程與實務建議可作為準備依據,但每家公司仍需依其邊界與適用規則判斷。 目前證據僅支持已揭露的事實與計畫,不足以證明所有預期效益已實現。
Regulatory milestones and practical guidance support preparation, but each company must determine applicability and boundaries. The current evidence supports only the disclosed facts and plans. It does not establish that every anticipated benefit has already been achieved.
產業與制度意涵
Industry & Institutional Implications盤查能力將逐步從永續部門任務轉為財務級資料治理。 對產業與制度而言,下一步關鍵是把資金、技術或政策標籤轉成可量測、可比較、可追溯的營運紀錄。
Inventory capability is moving from a sustainability-team task toward finance-grade data governance. For markets and institutions, the next step is to convert finance, technology or policy labels into measurable, comparable and traceable operating records.
SNN 編輯與揭露前證據基礎設施觀點
SNN Editorial / Pre-Disclosure Evidence Infrastructure PerspectiveSNN 編輯分析:此事件對台灣的金融、製造、能源、科技、運輸與供應鏈管理者具有治理借鏡。揭露前證據基礎設施應以穩定的事件、資產、契約、供應商與版本身分串接原始文件、計算方法、時間戳、責任人、核准狀態、例外、修正與查核軌跡。針對「企業溫室氣體盤查如何做到可查核,從原始憑證、方法鎖版到範疇 3 安全港」,企業不應只保存結論或新聞剪報,而應保存來源取得時間、適用邊界、基準年、分母、資料品質、估計值、實測值、控制措施與後續結果。台灣企業若引用相關減碳、韌性、自然或投資主張,董事會、財務、法遵、採購、永續與內部稽核應能讀取同一版證據,並看見尚未驗證、已撤回或被新資料取代的欄位。對供應鏈資料還需記錄誰提供、誰轉換、何時鎖版,以及跨系統傳遞是否改變單位或涵蓋範圍。這能降低在查核前臨時補件、把承諾誤寫成成果、或以單一數字掩蓋例外的風險。此段為 editorial analysis 與 editorial interpretation,不是來源已驗證事實。
SNN editorial analysis: This event offers governance lessons for Taiwan finance, manufacturing, energy, technology, transport and supply-chain teams. Pre-Disclosure Evidence Infrastructure should use stable identities for the event, asset, contract, supplier and version, then connect source documents, calculation methods, timestamps, accountable owners, approval state, exceptions, corrections and assurance history. For “How Companies Can Build an Audit-Ready GHG Inventory From Source Evidence to Method Control,” an organisation should retain more than a conclusion or news clipping. It should preserve when the source was retrieved, the applicable boundary, base year, denominator, data quality, estimates, measurements, controls and subsequent outcomes. If a Taiwan company relies on the related climate, resilience, nature or investment claim, its board, finance, compliance, procurement, sustainability and internal-audit teams should be able to inspect the same evidence version and see which fields remain unverified, were withdrawn, or were superseded. Supplier data should also show who supplied it, who transformed it, when it was locked and whether system transfers changed units or coverage. This reduces last-minute evidence reconstruction before assurance, prevents commitments from being reported as results and makes exceptions visible instead of hiding them behind one aggregate number. This paragraph is editorial interpretation, not a source-verified fact.
未來展望
Future Outlook後續應追蹤法規細節、確信範圍、範疇 3 方法與執法解釋。 任何後續實質更新都應新增版本並保留舊版,不應覆寫本次草稿。
Future updates should track regulatory detail, assurance scope, Scope 3 methods and enforcement interpretation. Any later material fact should create a new version while preserving this draft rather than overwriting it.
來源、證據鏈與責任編輯
來源媒體:ESG Today · 原文作者:Guest Post · 原文發布:
外部論述與制度來源
以下外部公告、法規、研究或新聞用於支撐本文論述,並與原始出版分開呈現。
- primary expert commentaryESG TodayBuilding an Audit-Ready GHG Inventory ↗出版日期 2026-09-08 · 查核時間 2026-09-09 11:18 (UTC+8)
Practical inventory controls, evidence retention and stated California reporting context.
- regulatory implementation contextCalifornia Air Resources BoardSB 253 March 2026 Workshop Slides ↗出版日期 2026-03-23 · 查核時間 2026-09-09 11:18 (UTC+8)
California corporate GHG reporting scope, proposed implementation timing and assurance rulemaking context.
- inventory-boundary methodGHG ProtocolCorporate Value Chain Scope 3 Accounting and Reporting Standard ↗出版日期 2011-10-04 · 查核時間 2026-09-09 11:18 (UTC+8)
Scope 3 categories, inventory boundary and value-chain accounting principles.
- assurance requirementsInternational Auditing and Assurance Standards BoardInternational Standard on Sustainability Assurance 5000 ↗出版日期 2024-11-12 · 查核時間 2026-09-09 11:18 (UTC+8)
General requirements for sustainability assurance engagements and evidence-quality expectations.
主題中心:永續制度與揭露