台灣焦點
歐盟 CBAM 新指引落地,台灣鋼鐵與扣件出口進入碳數據競爭
SNN.TW 編輯報導SNN.TW Editorial Reporting
歐盟執委會發布 CBAM 正式期十份指引,最新修正預設值資料為台灣設置獨立表單。台灣約 2,600 家鋼鐵與金屬扣件中小企業,正面臨從產品碳盤查走向可查證實際排放資料的出口競爭。
EU CBAM Guidance Puts Taiwan's Steel and Fastener Exports Into a Carbon Data Contest
The European Commission's ten definitive-period CBAM guides and corrected default-value workbook place Taiwan's steel and fastener exporters under a data-quality test, with about 2,600 SMEs exposed according to Taiwan's Ministry of Environment.
重點摘要
Executive Summary / Lead歐盟執委會於 2026 年 8 月 14 日發布 CBAM 正式期十份指引,並在 8 月 10 日更新修正後的預設值資料。最新官方資料以獨立工作表列出 Taiwan,台灣鋼鐵與金屬扣件出口的競爭條件,正從價格與品質延伸到可查證的產品碳數據。
On August 14, 2026, the European Commission published ten guides for the definitive CBAM period after issuing corrected default-value data on August 10. The official workbook gives Taiwan a dedicated country sheet, extending export competition for Taiwanese steel and fastener producers from price and quality to verifiable product-emissions data.
企業與產業背景
Company & Industry ContextCBAM 自 2026 年 1 月 1 日進入正式期,涵蓋水泥、鋼鐵、鋁、肥料、電力與氫。台灣環境部估計,國內主要受影響者是鋼鐵製品及金屬扣件等約 2,600 家中小企業,並已與經濟部啟動 CBAM 服務平台。
CBAM entered its definitive regime on January 1, 2026 and covers cement, iron and steel, aluminium, fertilisers, electricity and hydrogen. Taiwan's Ministry of Environment estimates that about 2,600 SMEs, mainly in steel products and metal fasteners, are affected and has launched a joint CBAM support platform with the Ministry of Economic Affairs.
挑戰與重要性
Challenge / Why It Matters歐盟進口商負有申報與憑證責任,但碳數據必須由台灣製造端向上游交付。若企業無法提供符合規則並經認可查驗的實際排放值,進口商可能改採歐盟預設值,而預設值另有逐年加成機制。
EU importers carry the declaration and certificate obligations, but Taiwanese manufacturers must supply the underlying carbon data. When actual emissions cannot be documented under the rules and verified by an accepted verifier, importers may rely on Commission default values, which are also subject to annual mark-ups.
行動、方案與執行
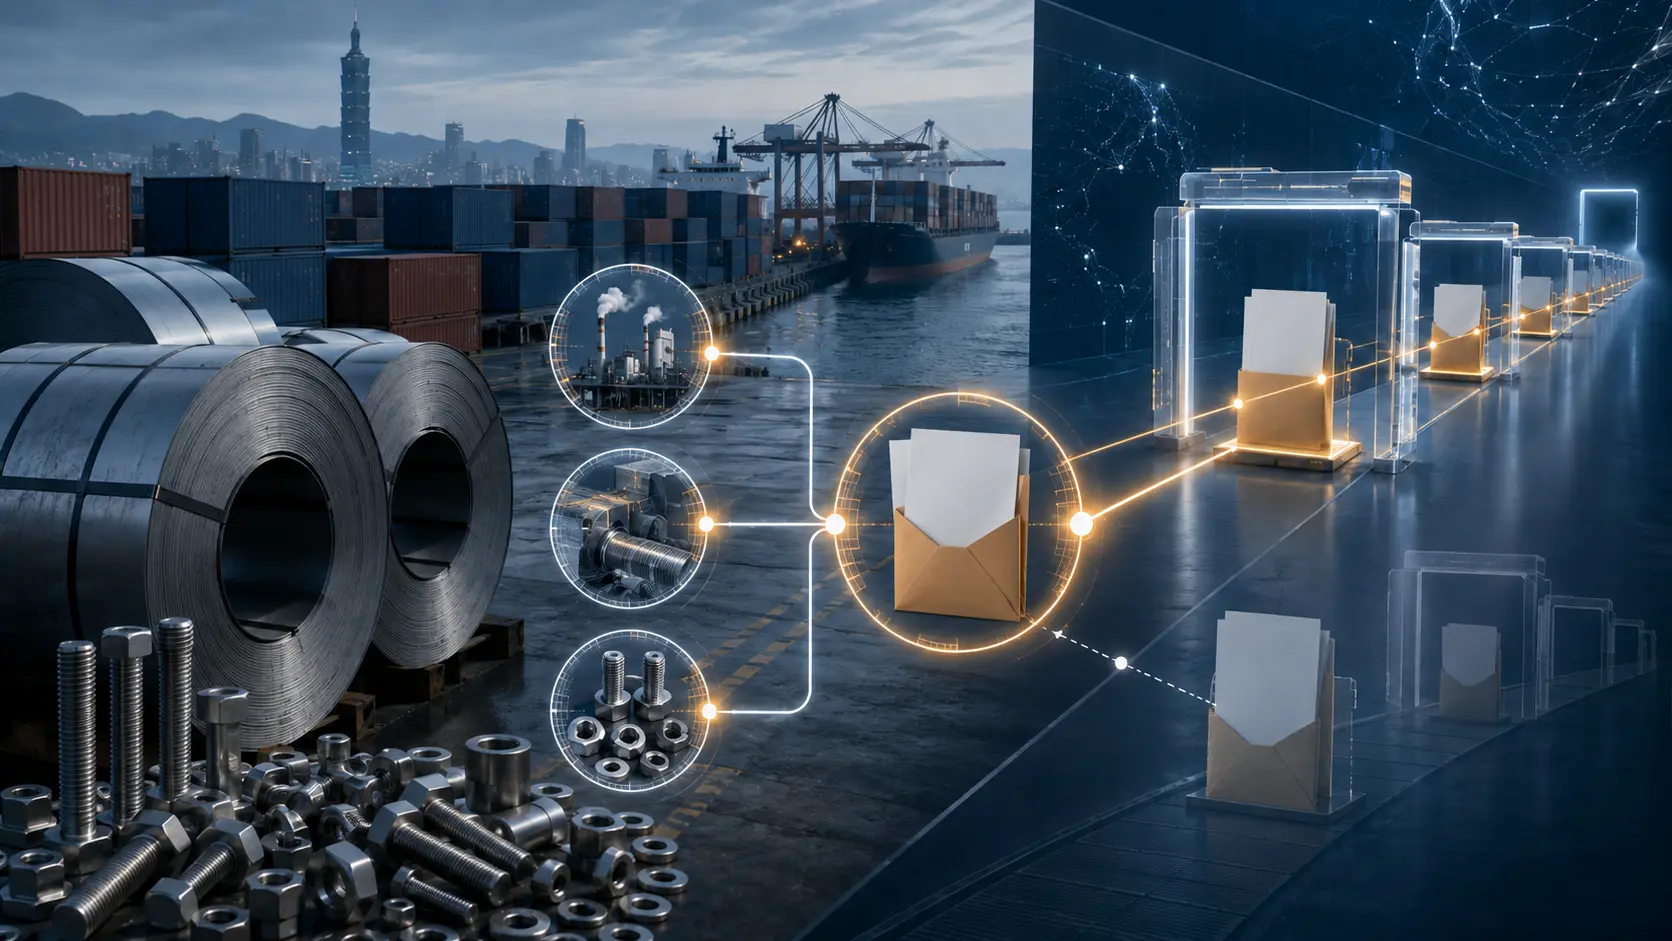
Action / Solution / Implementation十份指引要求非歐盟工廠建立監測計畫、界定製程與前驅物、保存活動數據,並把經查驗的實際排放資訊傳遞給授權 CBAM 申報人。台灣企業因此需要把產品代碼、工廠邊界、能源與原料、排放因子、查驗文件及客戶批次串成一致紀錄。
The ten guides direct non-EU installations to establish monitoring plans, define processes and precursors, retain activity data and communicate verified actual emissions to authorised CBAM declarants. Taiwanese exporters therefore need connected records for product codes, installation boundaries, energy and materials, emissions factors, verification files and customer batches.
證據、成果與影響
Evidence / Results / Impact歐盟 8 月 10 日修正版資料為 Taiwan 設置獨立工作表,其中 CN 7208 熱軋非合金鋼預設總排放值為每噸產品 2.310 噸二氧化碳當量,CN 7318 多項扣件子碼為 2.707。這些數值是資料不足時的制度性替代值,不是所有台灣工廠的實際排放,也不等於已發生的稅額或罰款。
The Commission's August 10 corrected workbook includes a Taiwan sheet. It lists a total default value of 2.310 tonnes of carbon dioxide equivalent per tonne for CN 7208 hot-rolled non-alloy steel and 2.707 for multiple CN 7318 fastener subcodes. These are regulatory substitutes when eligible data are unavailable, not the actual emissions of every Taiwanese plant and not a tax or penalty already incurred.
產業與制度意涵
Industry & Institutional Implications對台灣出口商而言,較低的實際排放只有在資料可計算、可查驗且可傳遞時才能形成商業優勢。CBAM 因此把碳管理從永續報告議題,轉為報價、客戶留存、供應鏈選擇與毛利管理問題。
Lower actual emissions become a commercial advantage only when they can be calculated, verified and transmitted. CBAM therefore moves carbon management beyond sustainability reporting into pricing, customer retention, supplier selection and margin management.
SNN 編輯與揭露前證據基礎設施觀點
SNN Editorial / Pre-Disclosure Evidence Infrastructure PerspectiveSNN 編輯分析:Taiwan 被列入官方國別預設值資料,不代表台灣遭到單獨制裁,也不應被渲染為巨額罰款。真正的風險是企業實際排放較低,卻因缺少可查驗證據而被預設值代表,讓資料缺口轉化為交易成本。
SNN editorial analysis: Taiwan's presence in the official country-specific default-value workbook does not mean that it has been singled out for sanctions, and it should not be framed as a massive fine. The material risk is that a lower-emitting producer may be represented by a default value because it lacks verifiable evidence, turning a data gap into a trade cost.
未來展望
Future Outlook後續應追蹤歐盟認可查驗機構、台灣碳費扣抵規則、2026 年實際出口批次申報,以及 2027 年首次憑證購買與年度申報結果。編輯審核亦應以歐盟後續修正版資料取代過時數值。
Further reporting should track EU-recognised verifiers, rules for deducting Taiwan's carbon fee, declarations for 2026 export batches, and the first certificate purchases and annual filings in 2027. Editorial review should also replace superseded figures whenever the Commission issues corrections.
來源、證據鏈與責任編輯
來源媒體:European Commission / Taiwan Ministry of Environment · 原文作者:SNN.TW 編輯台 · 原文發布:
外部論述與制度來源
以下外部公告、法規、研究或新聞用於支撐本文論述,並與原始出版分開呈現。
- Primary reporting sourceEuropean Commission / Taiwan Ministry of EnvironmentEuropean Commission / Taiwan Ministry of Environment 原始新聞來源 ↗出版日期 2026-08-14 · 查核時間 2026-08-25(時間未記錄)
本文主要事件、數據與引述所依據的原始新聞或公告來源。
- Supporting reporting or official source上游公告或報導來源補充來源 1 ↗出版日期 日期未標示 · 查核時間 2026-08-25(時間未記錄)
補充本文事件背景、制度脈絡、企業公告或相關事實。
- Supporting reporting or official source上游公告或報導來源補充來源 2 ↗出版日期 日期未標示 · 查核時間 2026-08-25(時間未記錄)
補充本文事件背景、制度脈絡、企業公告或相關事實。
- Supporting reporting or official source上游公告或報導來源補充來源 3 ↗出版日期 日期未標示 · 查核時間 2026-08-25(時間未記錄)
補充本文事件背景、制度脈絡、企業公告或相關事實。
- Supporting reporting or official source上游公告或報導來源補充來源 4 ↗出版日期 日期未標示 · 查核時間 2026-08-25(時間未記錄)
補充本文事件背景、制度脈絡、企業公告或相關事實。
- Supporting reporting or official source上游公告或報導來源補充來源 5 ↗出版日期 日期未標示 · 查核時間 2026-08-25(時間未記錄)
補充本文事件背景、制度脈絡、企業公告或相關事實。
主題中心:永續制度與揭露