議題探討
擔保品轉型:央行框架如何重定義永續資訊
歐洲央行把氣候因子從公司債擴大到合格企業信用債權,使轉型資訊更接近擔保品估值與流動性操作,也提高銀行對上游證據品質的需求。
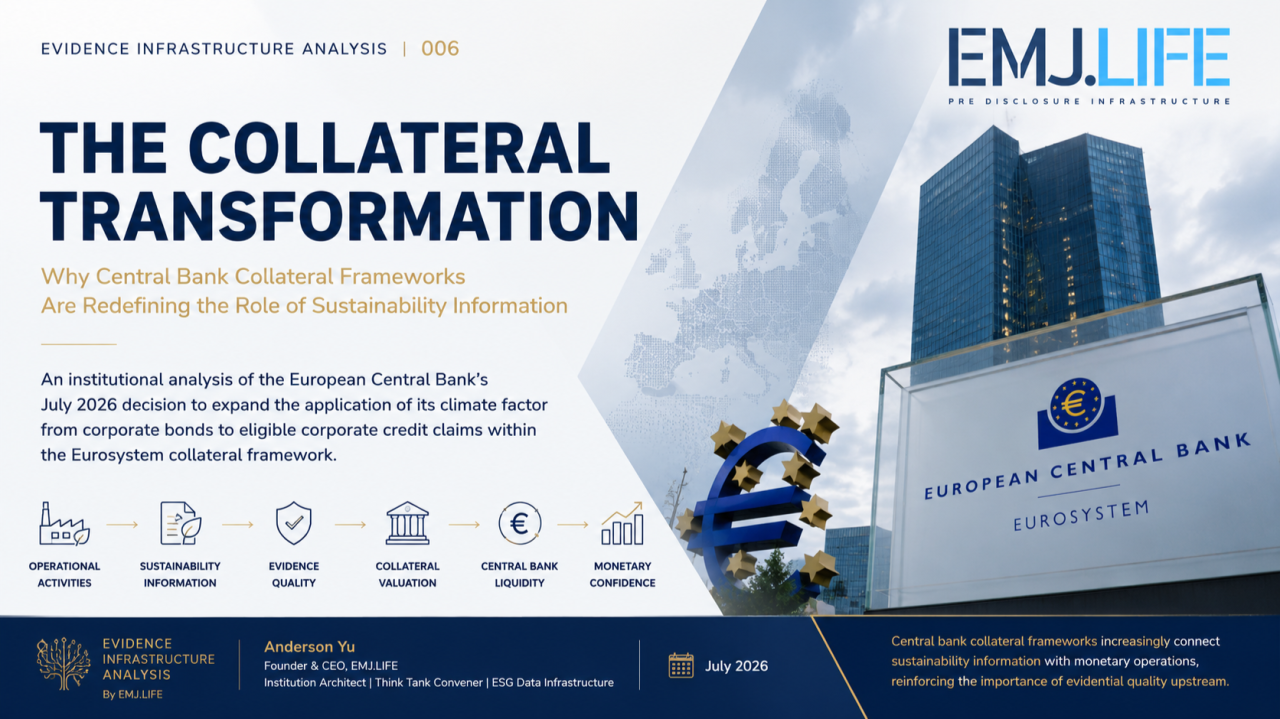
The Collateral Transformation: How Central Bank Frameworks Are Redefining Sustainability Information
The ECB's extension of its climate factor from corporate bonds to eligible corporate credit claims moves transition information closer to collateral valuation and liquidity operations.
重點摘要
Executive Summary / Lead歐洲央行將氣候因子從合格公司債擴大到合格企業信用債權,讓轉型風險資訊更接近歐元體系擔保品估值與流動性操作核心。 歐洲央行把氣候因子擴展到合格企業信用債權,重要性不在於建立另一套企業揭露規則,而在於永續資訊開始影響央行接受資產的風險處理。當銀行希望把企業貸款作為擔保品,轉型資訊便可能沿授信、資產分類、估值與流動性管理一路傳導。 本期 Analysis 因而不把 氣候因子進入央行擔保品框架後的資訊傳導 視為單一技術或政策更新,而是把官方主錨點可證明的制度事實、SNN 的分析推論與仍待驗證的結果分層處理。讀者必須能看見主張從何而來、推論在哪裡開始,以及哪些結論目前不能由來源直接支持。 為使摘要能直接支援決策,本段同時回答五個問題:已發生什麼、由哪一第一方紀錄支持、影響透過什麼機制傳導、目前仍缺少哪些結果證據,以及下一個可推翻或強化判斷的檢查點。任何未被來源明示的因果關係都保留為編輯推論,不以肯定語氣包裝。
The ECB has extended its climate factor from eligible corporate bonds to eligible corporate credit claims, moving transition-risk information closer to collateral valuation and Eurosystem liquidity operations. The ECB's extension of a climate factor to eligible corporate credit claims matters not because it creates another corporate disclosure regime, but because sustainability information begins to affect the risk treatment of assets accepted by a central bank. When a bank seeks to mobilise a corporate loan as collateral, transition information may travel through credit assessment, asset classification, valuation and liquidity management. This Analysis therefore does not treat the transmission of climate information through central-bank collateral frameworks as a self-contained technical or policy update. It separates the institutional facts supported by the official anchor, SNN editorial inference and outcomes that remain unverified. The reader should be able to see where the source ends, where interpretation begins and which conclusions the present evidence cannot support. To make the lead decision-ready, it answers five questions together: what has occurred, which first-party record supports it, through what mechanism the effect may travel, which outcome evidence is still missing, and what next observation could strengthen or overturn the judgement. Any causal relationship not stated by the source remains an editorial inference and is not converted into a factual claim through confident wording.
企業與產業背景
Company & Industry Context公司債主要位於資本市場,企業信用債權則由商業銀行產生。政策範圍擴大後,銀行成為連結企業營運資訊、信用風險與央行流動性的關鍵傳導層。 企業信用債權與公司債的資料形成路徑不同。前者多由銀行與客戶關係、契約及內部信用流程產生,後者通常伴隨資本市場揭露與外部資訊。氣候因子擴大後,銀行必須把企業層級資料映射到特定債權與擔保品資格,而不能只引用集團報告中的總體敘述。 為了維持分析密度,制度背景必須同時標示規則制定者、執行者、資料擁有人、覆核者與受影響市場。這些角色可能由不同組織或部門承擔;文件發布、系統上線、企業採用與結果交付也不是同一證據狀態。 時間與權限也必須分開記錄:公告日不等於生效日,試點不等於普遍採用,技術規格不等於法律義務,企業自願導入也不等於監理核准。把這些節點放在同一時間軸,才能判斷一項制度變動何時真正進入資料、合約、投資或揭露流程。
Corporate bonds sit mainly in capital markets, while credit claims originate in commercial banking. The expanded scope makes banks a key transmission layer between corporate operations, credit risk and central-bank liquidity. Corporate credit claims and bonds have different data-formation paths. The former are generated largely through bank-customer relationships, contracts and internal credit processes; the latter normally carry capital-market disclosures and external information. With an expanded climate factor, a bank must map company-level information to a specific claim and collateral eligibility rather than rely only on group-level reporting narrative. Institutional context must identify the rule setter, implementer, data owner, reviewer and affected market. Those roles may sit in different organisations or functions, and publication of a document, deployment of a system, enterprise adoption and delivery of an outcome are different evidence states. Time and authority must also be separated. An announcement date is not an effective date; a pilot is not general adoption; a technical specification is not a legal obligation; and voluntary enterprise use is not regulatory approval. Putting these events on one timeline shows when an institutional development actually enters data, contract, investment or disclosure processes and which actor is authorised to make that transition.
挑戰與重要性
Challenge / Why It Matters法律上的永續揭露豁免不必然等於融資豁免。若銀行為擔保品管理需要可靠轉型資訊,資訊要求可能透過授信關係延伸到法定揭露範圍之外。 法律揭露豁免與金融資料需求的錯位,是主要治理風險。中小企業即使不在強制揭露範圍,仍可能因授信或供應鏈關係被要求提供轉型資訊;若銀行使用不透明代理值,企業難以修正錯誤,若各銀行採用不同人口、期間與方法,同一企業也可能形成多個不一致的氣候風險身分。 上游證據若沒有穩定識別、形成時間、適用邊界與版本,最終輸出即使格式一致,覆核者仍可能無法重建形成過程。真正風險不是單一欄位缺失,而是錯誤主體、過期方法、推定關係或未核准版本在傳遞中被當成確定事實。 具體失效模式至少包括主體配對錯誤、資料人口不完整、邊界前後不一致、方法或係數未版本化、例外未留下理由、核准與發布時間倒置,以及下游重用時脫離原用途。每一種失效都可能讓合理的單筆資料,在彙總後形成無法防禦的結論。
An exemption from statutory sustainability reporting does not necessarily create a financing exemption. Banks may request reliable transition information for collateral management beyond the legal boundaries of disclosure rules. A mismatch between legal disclosure exemptions and financial data demand is the main governance risk. Smaller firms outside mandatory reporting may still be asked for transition information through lending or supply-chain relationships. If banks use opaque proxies, companies cannot correct errors; if banks use different populations, periods and methods, one enterprise can acquire multiple inconsistent climate-risk identities. When upstream evidence lacks stable identity, formation time, applicable boundary and version, a standardised output may still be impossible to reconstruct. The material risk is not one missing field. It is the silent conversion of the wrong entity, an expired method, an inferred relationship or an unapproved version into an apparent fact as information moves downstream. Concrete failure modes include incorrect entity matching, an incomplete data population, inconsistent boundaries, unversioned methods or factors, exceptions without rationale, approval occurring after publication, and downstream reuse outside the original purpose. Each failure can turn a reasonable individual record into a conclusion that cannot be defended after aggregation, comparison or machine-assisted interpretation.
行動、方案與執行
Action / Solution / Implementation銀行可把轉型資訊的來源、方法、時間、責任與資產識別連結到信用及擔保品流程,降低資訊在企業、授信評估與央行操作之間的失真。 銀行可為企業、交易對手、信用債權、擔保品池與氣候因子建立可追溯映射,保存資料來源、報導期間、估算方法、客戶確認、內部覆核與適用版本。當企業資料更新、債權轉讓或方法調整時,系統應顯示哪些估值與流動性決策受到影響,而不是覆寫先前結果。 可執行的控制單位應是受治理的證據物件:每項重要主張連接原始來源、計算或判斷方法、組織與時間邊界、責任人、控制狀態、例外、核准及版本。當任何元件改變時,系統保存差異與影響範圍,不以覆寫舊檔取代變更紀錄。 營運上可建立最小控制集:主張登錄、證據擁有人、來源快照、方法識別、適用期間、控制頻率、例外門檻、覆核與核准,以及允許的下游用途。高判斷或高財務影響項目採更嚴格的覆核層級;低風險資料則以自動化完整性檢查降低重工。
Banks can bind the provenance, method, time, responsibility and asset identity of transition information to credit and collateral workflows, reducing distortion between corporate operations, lending assessment and monetary operations. Banks can create traceable mappings among enterprises, counterparties, credit claims, collateral pools and climate factors, preserving source, reporting period, estimation method, customer confirmation, internal review and applicable version. When company data change, a claim is transferred or methodology is revised, the system should show which valuation and liquidity decisions are affected instead of overwriting the earlier result. The implementable control unit is a governed evidence object. Each material claim links to its primary source, calculation or judgement method, organisational and temporal boundary, accountable owner, control state, exception, approval and version. When any component changes, the system preserves the difference and affected uses instead of overwriting the earlier basis. A minimum operating control set includes a claim register, evidence owner, source snapshot, method identity, valid period, control frequency, exception threshold, review, approval and permitted downstream use. High-judgement or high-financial-impact items receive a stronger review tier. Lower-risk records use automated completeness and consistency checks so that governance effort is concentrated where a wrong claim would change a decision.
證據、成果與影響
Evidence / Results / ImpactECB 公告確認氣候因子適用範圍擴大至企業信用債權。這不是新的企業揭露制度,而是對哪些金融資產如何在歐元體系中被評價的調整。 ECB 公告能支持政策範圍擴大與氣候因素進入企業信用債權處理的事實,但不等於企業貸款價值將依單一公式立即變動,也不創設台灣企業的直接法律義務。本文分析的是可能的金融傳導與證據需求,實際效果仍取決於歐元體系方法、銀行實作與個別資產條件。 證據判讀以本期官方主錨點為起點,再以獨立第一方或具方法透明度的來源確認背景與邊界。來源能支持的是已發布的制度事實與明確數據;是否代表全面採用、因果改善或跨市場普遍有效,必須另有實作結果才能成立。 每一項關鍵句都應進入 claim ledger,標示其為官方事實、直接量測、估算、企業承諾、已交付結果或 SNN 編輯推論,並記錄來源所能支持的精確範圍。若兩筆來源衝突,保留衝突與處理理由;若資料尚未出現,明確標成待驗證,而不是以相近案例補成確定答案。
The ECB announcement confirms that corporate credit claims enter the climate-factor scope. It does not create a new corporate disclosure regime; it adjusts the evaluation of assets used within the Eurosystem. The ECB announcement supports the fact that policy scope is expanding and climate considerations are entering the treatment of corporate credit claims. It does not imply that loan values will immediately change through one formula and does not impose a direct legal obligation on Taiwan enterprises. This Analysis concerns potential financial transmission and evidence demand; actual effects depend on Eurosystem methodology, bank implementation and asset conditions. Evidence assessment begins with the official anchor and uses independent primary or method-transparent sources to test context and limits. The sources support stated institutional facts and explicit figures. Claims of comprehensive adoption, causal improvement or universal cross-market effectiveness require separate implementation evidence. Every material sentence should enter a claim ledger and be classified as official fact, direct measurement, estimate, corporate commitment, delivered outcome or SNN editorial inference. The ledger records the precise scope that each source supports. Conflicting evidence is retained with the resolution rationale; absent evidence is marked pending rather than filled with a convenient analogue from another entity, period or jurisdiction.
產業與制度意涵
Industry & Institutional Implications永續資訊開始影響的不只是投資者判斷,也包含擔保品價值、流動性與資產負債表管理。銀行內部方法可能因此逐步走向跨市場一致。 這項變化使永續資訊從投資人溝通進一步進入資產負債表與流動性治理。資料品質問題可能轉化為較保守的代理值、較高的內部風險權重或額外客戶查詢。能夠把轉型計畫、資產、排放與融資用途連結的企業,較有能力解釋自身風險;只有政策承諾的企業則可能被外部估算定義。 這種資訊密度的目的不是增加篇幅,而是縮短主張到決策之間的查核距離。董事會、投資人、監理者與營運團隊應能辨識哪些內容是事實、估算、承諾、進度或結果,並在情境改變時更新判斷,而不是重新尋找散落的檔案與口頭說明。 責任分工因此必須落到決策權:資料擁有人維護來源,方法擁有人控制計算,業務單位說明使用情境,內控或確信人員測試可重建性,核准者承擔最終採用責任。例外若沒有到期日、補救人與影響範圍,就會從暫時處置變成永久的證據債務。
Sustainability information may now affect collateral value, liquidity and balance-sheet management, not only investor decisions. Integrated banking groups may therefore move toward more consistent methods across markets. The change moves sustainability information beyond investor communication into balance-sheet and liquidity governance. Weak data may result in conservative proxies, higher internal risk treatment or additional customer enquiries. An enterprise able to connect its transition plan to assets, emissions and financing purpose can explain its risk more effectively; one offering only policy commitments may instead be defined by external estimates. The purpose of this information density is not length for its own sake. It is to shorten the verification distance between claim and decision. Boards, investors, regulators and operational teams should be able to distinguish fact, estimate, commitment, progress and outcome, then update the judgement when conditions change without reconstructing the case from scattered files and oral explanation. Accountability therefore attaches to decision rights. The data owner maintains the source, the method owner controls calculation, the business function defines the use case, internal control or assurance tests reproducibility, and the approver accepts responsibility for final use. An exception without an expiry date, remediation owner and impact scope stops being temporary treatment and becomes persistent evidence debt.
SNN 編輯與揭露前證據基礎設施觀點
SNN Editorial / Pre-Disclosure Evidence Infrastructure PerspectiveSNN 編輯分析:歐洲央行把氣候因素帶入擔保品框架,顯示永續資訊將逐步影響資金價格與流動性。台灣銀行、公司債發行人、出口企業與金融機構應讓轉型計畫、排放、資產、交易對手及查驗狀態可被串連;否則歐洲政策變動會在授信或市場估值時才突然反映。 台灣銀行與歐洲金融機構往來、台灣企業向歐洲銀行融資或進入歐洲供應鏈時,都可能感受到這類資料要求。金融機構應區分法規揭露、授信評估與擔保品用途,企業則應把轉型計畫連到設施、資本支出、排放基準、里程碑與查驗狀態,避免同一份永續報告被當成所有信用決策的唯一證據。 對台灣市場的意義應沿實際傳導路徑判斷:國際制度或客戶要求先進入融資、採購、合約、供應商資料與確信流程,再影響台灣企業的系統與控制。這不等於外國規則自動成為台灣法律義務;本地企業要做的是辨識適用情境、保留跨語言對應並建立可授權覆核的證據鏈。 台灣企業可把傳導測試落在具體物件:公司與法律主體、廠區、產品、批次、供應商、合約、融資工具及揭露欄位。中英文名稱、內外部分類與不同框架之間應連到同一主張識別,同時保留商業機密、個資與權限邊界,避免可追溯被誤解為全面公開。
SNN editorial analysis: The European Central Bank move to incorporate climate factors into collateral frameworks shows sustainability information moving into funding cost and liquidity. Taiwan banks, bond issuers, exporters and financial institutions need connected transition plans, emissions, assets, counterparties and assurance status before European policy changes surface abruptly in credit or valuation. Taiwan banks interacting with European financial institutions, Taiwan companies borrowing from European banks and suppliers entering European value chains may all encounter this type of data request. Financial institutions should distinguish regulatory disclosure, credit assessment and collateral use. Companies should connect transition plans to facilities, capital expenditure, emissions baselines, milestones and verification status rather than allow one sustainability report to serve as universal evidence. For Taiwan, relevance should be traced through an actual transmission path. An international rule or customer requirement first enters finance, procurement, contract, supplier-data and assurance processes, then changes local systems and controls. It does not automatically become Taiwan law. Companies need to identify the applicable scenario, preserve bilingual mappings and make the evidence chain reviewable under controlled access. Taiwan companies can perform the transmission test on concrete objects: the company and legal entity, facility, product, batch, supplier, contract, financing instrument and disclosure field. Chinese and English names, internal and external classifications and different reporting frameworks should resolve to the same claim identity. Traceability must still preserve commercial confidentiality, personal data and access boundaries; it does not require unrestricted publication.
未來展望
Future Outlook未來需觀察銀行如何調整信用資料、擔保品管理與客戶要求,以及其他央行是否採用類似機制。人工審核應核對 ECB 公告與實際施行時間。 後續應觀察 ECB 方法細節、銀行如何取得客戶資料、代理值是否可被挑戰,以及其他央行是否採類似設計。低後悔準備是由銀行與企業共同測試一筆信用債權:能否從氣候因子結果回到企業資料、方法版本、覆核人與適用資產,並在資料改變後辨識受影響的決策。 後續追蹤應分開最終文件、技術指引、採用範圍、執行控制、監督活動與可觀察結果。現階段的低後悔行動,是挑選一項高風險主張做端到端重建測試,記錄缺少的身分、來源、方法、責任與版本;這是治理準備,不是合規保證或結果預測。 監測不只依日曆,而應由事件觸發:最終規則發布、技術指引變更、適用範圍擴大、主管機關執法、企業採用數據或實際成果出現時,都建立新版本並重評原判斷。舊結論不刪除,而是標示當時依據、被何種新證據修正,以及哪些決策需要重新檢視。
Future review should examine changes in bank credit data, collateral management and customer information requests, as well as possible diffusion to other central banks. Editors must verify the ECB announcement and implementation timeline. Future work should examine ECB methodological detail, bank customer-data practices, whether proxies can be challenged and whether other central banks adopt similar designs. A low-regret test is for a bank and company to select one credit claim and determine whether a climate-factor result can be traced to company data, method version, reviewer and applicable asset, and whether changed data reveal every affected decision. Future monitoring should separate final text, technical guidance, adoption scope, operating controls, supervision and observable outcomes. A low-regret step is to select one high-risk claim for an end-to-end reconstruction test and record missing identity, source, method, accountability and version. That is governance preparation, not a compliance guarantee or forecast of results. Monitoring should be event-triggered as well as calendar-based. A final rule, amended technical guidance, expanded scope, supervisory action, adoption data or observed outcome creates a new version and a reassessment of the earlier judgement. The prior conclusion is not erased. It retains its original basis, identifies the new evidence that changed it and states which decisions or downstream uses now require review.
來源、證據鏈與責任編輯
來源媒體:sustainabilitynewsnetwork.net · 原文作者:Anderson Yu · 原文發布:
原始出版
外部論述與制度來源
以下外部公告、法規、研究或新聞用於支撐本文論述,並與原始出版分開呈現。
- Primary analysis sourceEuropean Central BankECB expands climate factor to corporate credit claims ↗出版日期 日期未標示 · 查核時間 2026-08-17 03:26 (UTC+8)
Official primary source selected through publication-level web research.
- Taiwan market-context source金融監督管理委員會永續經濟活動認定參考指引與轉型計畫建議涵蓋事項 ↗出版日期 2024-12-31 · 查核時間 2026-08-25(時間未記錄)
Supports Taiwan use of sustainability evidence in lending, investment, insurance, sustainable securities and transition decisions.