議題探討
永續資料如何接上交易:從供應商排放到財務決策的控制問題
SNN.TW 編輯報導SNN.TW Editorial Reporting
Trellis 的 SAP 贊助評論提出永續資料的三項障礙。SNN 以原始制度文件及獨立風險分析,檢視跨制度轉換、供應商資料與交易連結的限制。
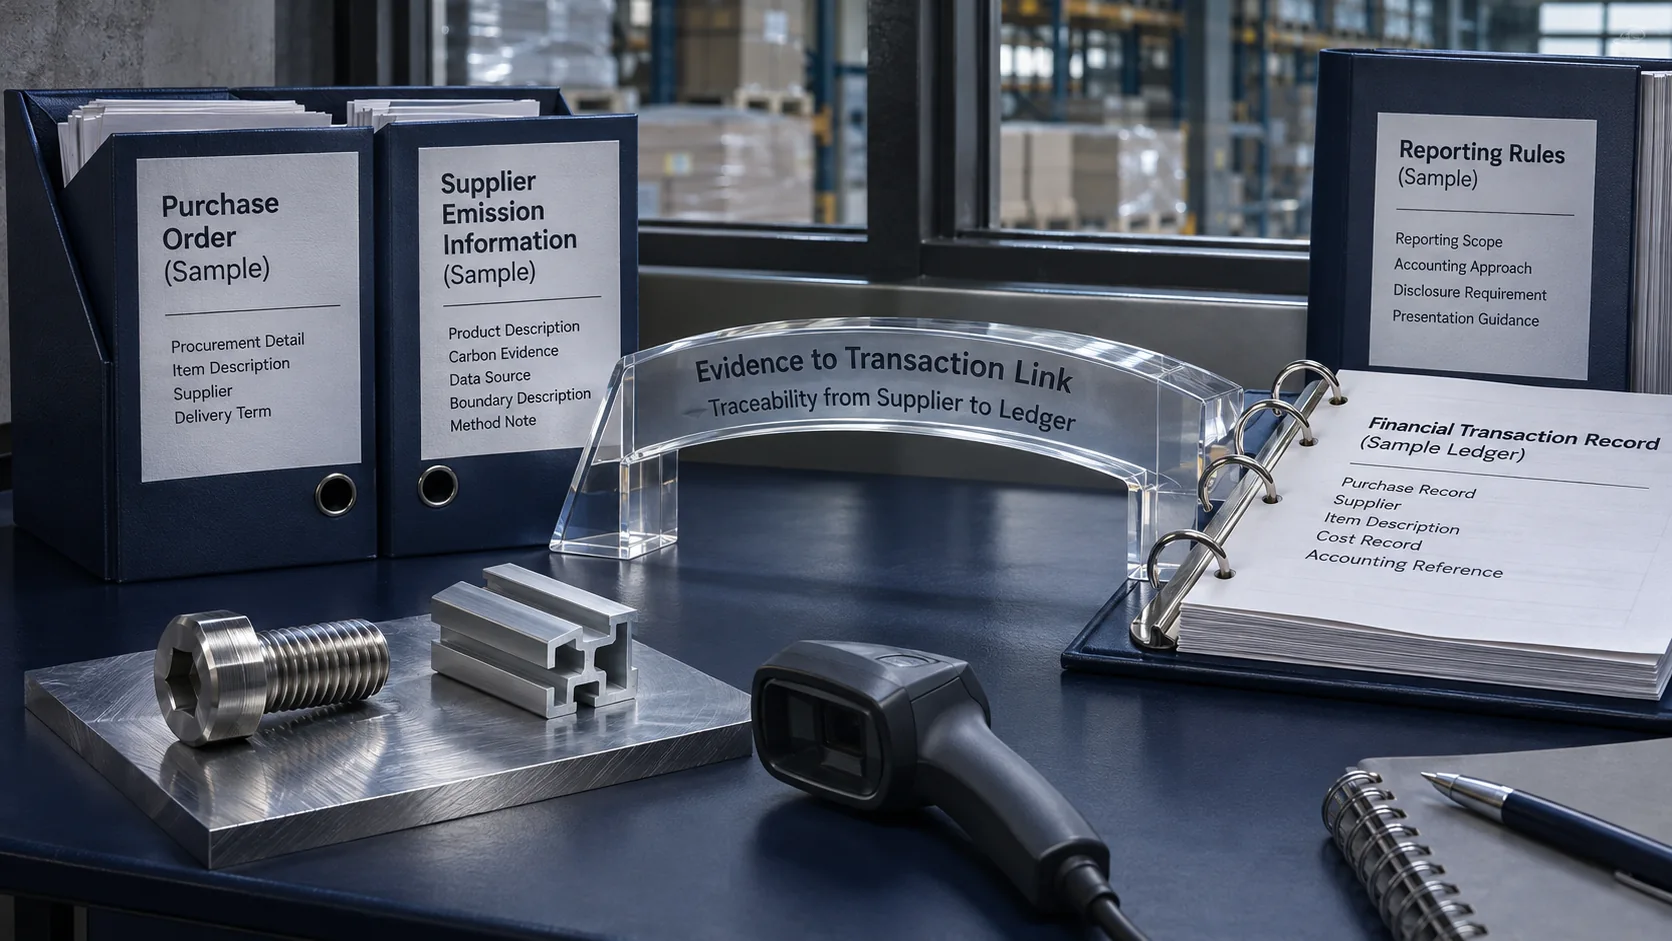
Connecting supplier carbon evidence with transaction records and financial decisions
A SAP-sponsored Trellis commentary identifies three sustainability-data hurdles. SNN examines interoperability, supplier evidence and transaction links against formal rules and independent risk analysis.
重點摘要
重點摘要Trellis 於 11 月 12 日刊出 Sophia Mendelsohn 的 SAP 贊助評論,討論永續資料分散、品質不足及與營運脫節的問題。SNN 將這篇文章視為具商業立場的分析來源,進一步檢視其中的制度與資料主張,不把產品介紹當成獨立成效證明。
A SAP-sponsored commentary by Sophia Mendelsohn, published by Trellis on November 12, examines fragmented, weak and operationally disconnected sustainability data. SNN treats it as analysis with an identified commercial perspective and tests its institutional and data propositions separately. A product description is not independent evidence of customer outcomes.
企業與產業背景
企業與產業背景供應商、採購部門、碳盤查人員與財務人員,經常依不同目的整理同一筆交易。供應商排放資料需要期間與邊界,採購紀錄需要品項及交付,財務紀錄則需要成本與責任歸屬。共同平台可能改善連結,但系統名稱本身不能確定各欄位是否具有相同意義。
Suppliers, procurement staff, carbon-accounting specialists and finance teams often organise the same transaction for different purposes. Emissions records need periods and boundaries, purchase records need items and delivery, and financial records need cost attribution. A shared platform may improve connections, but its name does not establish that fields mean the same thing.
挑戰與重要性
挑戰與重要性GHG Protocol 的正式標準發展說明提出與 ISO 整合企業碳會計準則的工作。KPMG 的獨立專業分析提醒,ISSB 或歐盟是否、何時引用修訂內容,仍須另行考慮。SNN 的判讀是,降低碎片化的方向,不等於所有現行規則已經合併,也不適合成為延後整理資料的理由。
GHG Protocol’s formal development plan proposes combining corporate carbon-accounting standards with ISO. KPMG’s independent professional analysis notes that incorporation by the ISSB or European Commission requires separate consideration. SNN interprets the direction toward less fragmentation as different from a completed merger of current reporting obligations, and as no reason to postpone data preparation.
行動方案與執行
行動方案與執行供應商實際資料與預設值的選擇,必須回到具體制度與商品。歐盟 2026/1740 正式文件修正 CBAM 預設值附件與計算呈現,顯示商品代碼、生產路徑及版本均會影響使用方式。本文不將單一加成率套用所有商品,也不以供應商自行提供的數字直接認定可被法規採用。
Choosing supplier-specific information or default values requires the relevant rule and good. The authentic EU 2026/1740 instrument corrects CBAM default-value annexes and calculation presentation, illustrating why product codes, production routes and versions matter. This article does not apply one mark-up to every good or assume that a supplier’s own number automatically qualifies for regulatory use.
證據成果與影響
證據成果與影響SAP 5 月的第一方文章描述其把財務、營運與永續資料放進 ERP 流程的產品方向;這能證明廠商如何陳述方案,不能證明每個客戶已節省成本。NIST 的獨立生成式 AI 風險資料,則支持對自動解讀、資訊完整性及人員覆核進行控制,而非讓模型自行決定制度間的對應。
SAP’s dated May first-party article describes its approach to embedding financial, operational and sustainability data in ERP workflows. It establishes how the vendor presents its offering, rather than verified savings for each customer. The independent NIST generative-AI risk profile supports controls for automated interpretation, information integrity and human review, rather than delegating institutional mappings to a model.
產業與制度意涵
產業與制度意涵SNN 的分析是,一筆排放數字若無法連回供應商、商品、期間及原始紀錄,接到財務系統後仍可能保留相同缺口。資料互通應同時保存不能互換的差異。真正可評估的進展,是抽樣時能否重建資料來源、計算與交易關係,而非只看儀表板是否更完整。
SNN’s analysis is that connecting a carbon figure to a finance system does not repair a missing supplier, item, period or source record. Interoperability should preserve differences that cannot be exchanged. A meaningful test is whether a sample can reconstruct the source, calculation and transaction relationship, rather than whether a dashboard appears more complete.
SNN 編輯與揭露前證據基礎設施觀點
SNN 編輯與揭露前證據基礎設施觀點SNN 編輯分析與建議:揭露前證據基礎設施可把供應商排放與交易證據接成可檢查的關係。歐盟進口申報及跨國採購若提高原始資料要求,可能透過進口商與 ERP 介面規格,傳導為台灣鋼鋁出口採購團隊及企業 ERP 財會整合團隊的資料工作;不代表贊助文章已證明台灣企業導入成效。台灣鋼鋁出口採購團隊應在每批交付進口商資料前,核對商品代碼清冊、供應商製程排放檔案與原產地紀錄,確認採用版本及缺漏。台灣企業 ERP 財會整合團隊應在新介面上線前,抽樣比對採購單號、供應商發票及碳計算版本,記錄無法連結或被重複配對的交易。台灣碳盤查覆核團隊應在規則附件或供應商資料更新時,依預設值版本清單與人工例外處置日誌重算受影響項目,並保留變更前後結果。以上為條件式編輯建議,採用特定產品及資料可否供申報使用,仍需分別驗證。
SNN editorial analysis: Pre-Disclosure Evidence Infrastructure can make supplier emissions and transaction evidence inspectable together. If EU import reporting and multinational procurement demand more primary data, importer requests and ERP interface specifications may transmit that demand to Taiwan steel-and-aluminium export procurement teams and enterprise ERP-finance integration teams. This does not establish that the sponsored commentary proves implementation outcomes in Taiwan. Taiwan steel-and-aluminium export procurement teams should reconcile the product-code roster, supplier process-emissions files and origin records before each dataset delivery to an importer, identifying versions and gaps. Taiwan enterprise ERP-finance integration teams should sample purchase-order identifiers, supplier invoices and carbon calculation versions before a new interface goes live, logging unmatched or multiply matched transactions. Taiwan carbon-inventory review teams should recalculate affected items against the default-value version list and human exception-disposition log whenever rule annexes or supplier data change, retaining both previous and revised results. These are conditional editorial recommendations; product selection and regulatory usability require separate verification.
未來展望
未來展望未來可要求的證據,包括明確的資料責任、可重跑的計算、介面錯誤處理與實際使用者驗證。軟體擴充、制度簡化及 AI 輔助可以同時推進,但不能互相替代。評估方案時,宜以具體交易抽樣與可重建結果,檢驗供應商主張。
Useful evidence of progress includes assigned data responsibilities, reproducible calculations, interface-error handling and actual user validation. Software expansion, institutional simplification and AI support can proceed together, while remaining separate contributions. Transaction sampling and reconstructable results provide a practical basis for testing a supplier’s claims.
來源、證據鏈與責任編輯
來源媒體:Trellis · 原文作者:Sophia Mendelsohn · 原文發布:
外部論述與制度來源
以下外部公告、法規、研究或新聞用於支撐本文論述,並與原始出版分開呈現。
- New SAP-sponsored commentary connecting fragmented reporting, supplier data and transaction records. Vendor claims identified as such; not independent product validation.TrellisThree data hurdles businesses face as COP31 turns to implementation ↗出版日期 2026-11-12 · 查核時間 2026-11-13 12:15 (UTC+8)
New SAP-sponsored commentary connecting fragmented reporting, supplier data and transaction records. Vendor claims identified as such; not independent product validation.
- Vendor’s own dated description of ERP-embedded financial/operational/sustainability data and supplier-level reporting capabilities. Not an independent IDC audit or proof of customer savings.SAP SESAP Named a Leader in the IDC MarketScape:Worldwide Carbon Accounting and Management Applications2026 Vendor Assessment ↗出版日期 2026-05-01 · 查核時間 2026-11-13 12:49 (UTC+8)
Vendor’s own dated description of ERP-embedded financial/operational/sustainability data and supplier-level reporting capabilities. Not an independent IDC audit or proof of customer savings.
- Formal standard-development plan aligns corporate carbon standards with ISO,with proposal consultation2027 and intended final2028. Existing rules remain distinct from future revisions.GHG Protocol / WRI / WBCSDGHG Protocol Announces Key Standard Development Updates:FAQ Resource ↗出版日期 2026-07-29 · 查核時間 2026-11-13 12:28 (UTC+8)
Formal standard-development plan aligns corporate carbon standards with ISO,with proposal consultation2027 and intended final2028. Existing rules remain distinct from future revisions.
- Authentic published default-value correction and annex distinguish goods,production routes and mark-ups. Supports the importance of CN-code/country-specific data and corrected version control,not a universal rate for all goods.European Union Official Journal / European CommissionCommission Implementing Regulation(EU)2026/1740 correcting Annexes I and IV to2025/2621 ↗出版日期 2026-07-31 · 查核時間 2026-11-13 12:28 (UTC+8)
Authentic published default-value correction and annex distinguish goods,production routes and mark-ups. Supports the importance of CN-code/country-specific data and corrected version control,not a universal rate for all goods.
- Original risk profile identifies confabulation,information integrity and human-AI configuration risks,and corresponding provenance/testing/monitoring practices. Independently supports the guide’s central warning that bounded inputs and review are needed;does not audit company pilots.US National Institute of Standards and TechnologyArtificial Intelligence Risk Management Framework:Generative Artificial Intelligence Profile,NIST AI600-1 ↗出版日期 2024-07-26 · 查核時間 2026-11-13 12:23 (UTC+8)
Original risk profile identifies confabulation,information integrity and human-AI configuration risks,and corresponding provenance/testing/monitoring practices. Independently supports the guide’s central warning that bounded inputs and review are needed;does not audit company pilots.
- Original professional analysis explains existing reporting references and need for separate ISSB/Commission consideration of whether/when to embed a revised standard. Directly supports the article’s interoperability/adoption boundary and transition-management advice.KPMG InternationalGHG Protocol and ISO to align standards ↗出版日期 2026-07-31 · 查核時間 2026-11-13 12:28 (UTC+8)
Original professional analysis explains existing reporting references and need for separate ISSB/Commission consideration of whether/when to embed a revised standard. Directly supports the article’s interoperability/adoption boundary and transition-management advice.
主題中心:永續制度與揭露