議題探討
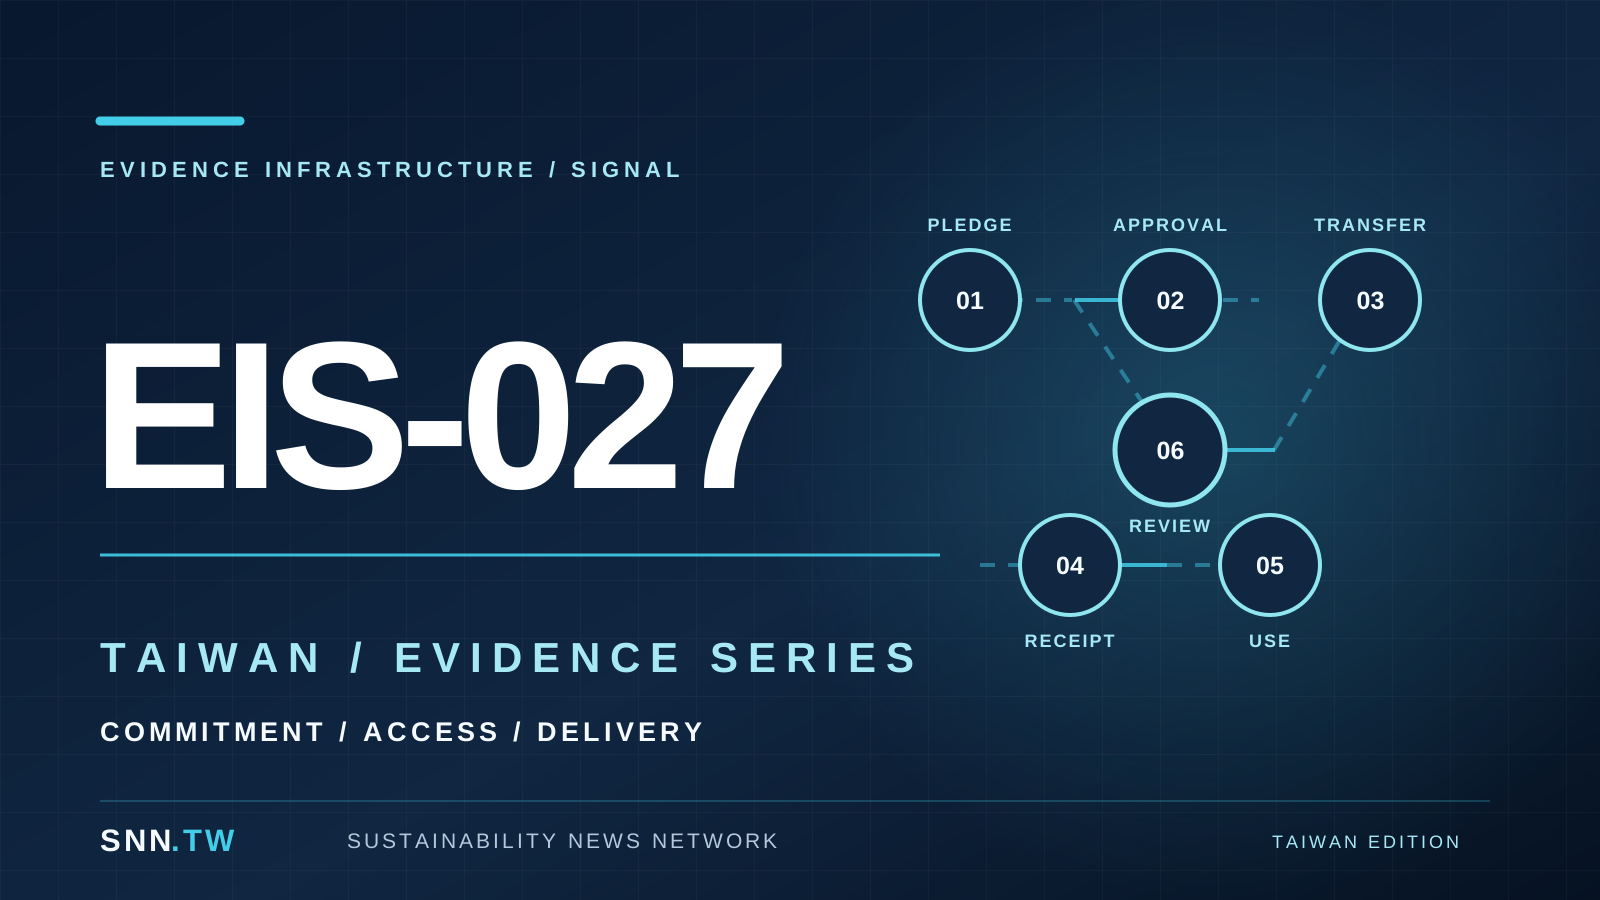
EIS-027|誰能證明交付?台灣氣候與自然融資從承諾、撥付到執行的證據鏈
SNN.TW 制度解讀SNN.TW Institutional Interpretation
全球氣候與自然融資承諾如何進入台灣市場?本篇將核准、撥付、收受、執行與成果分開,追蹤上市櫃企業、金融、採購及地方執行者在揭露前所需的證據與權責。
本文身分與雙語引用
Article identity and bilingual citation
- 內容身分 Identity
- SNN.TW 台灣獨立解讀 · SNN.TW 制度解讀Independent Taiwan interpretation · SNN.TW Institutional Interpretation
- 語言 Languages
- 繁體中文及英文同頁 · 同一本站 canonicalTraditional Chinese and English on the same local canonical
- 發布/版本 Published / version
- 2026-11-05T16:00:00.000Z · v10 · 更新 2026-11-06T09:52:49.560Z2026-11-05T16:00:00.000Z · v10 · Updated 2026-11-06T09:52:49.560Z
- 本站正典 Local canonical
- https://snn.tw/article/eis-027-who-can-prove-delivery
- 全球脈絡 Global starting point
- EIS-027 · sustainabilitynewsnetwork.net ↗Starting point for independent Taiwan interpretation; no translation equivalence asserted.
Publisher/編輯責任:SNN.TW。樞紐閱讀:台灣永續揭露、TNFD 與自然證據、AI 治理與採購、供應鏈與人權盡職調查、永續金融與投信治理。Publisher and editorial controller: SNN.TW.
台灣法律與政策狀態
Taiwan legal and policy state, by source
本文編輯判讀:《氣候變遷因應法》與風險評估準則在其政府權責範圍內屬現行法規;國家計畫及金融政策是政策脈絡;FSC新聞公告不能代替正式修正條文;永續經濟活動及TNFD指引屬自願參考。
The Climate Change Response Act and risk-assessment regulation bind competent authorities within scope; national plans and green-finance programmes provide policy context. An FSC news notice does not replace operative amended text. Activity and TNFD guidance remain voluntary references.
現行具拘束力規則 CURRENT_BINDING_RULECurrent binding rule
文件日期:2023-02-15 · 查核日期:2026-11-06T07:48:31.627Z
支持範圍:Articles 17–20 allocate adaptation planning to competent authorities
限制:正式法規;不使所有私人企業負同一政府計畫義務
僅供背景參考 CONTEXT_ONLYContext only
文件日期:2023-10-25 · 查核日期:2026-11-06T07:48:31.627Z
支持範圍:Seven sectors and 126 government projects
限制:Earmarked budget is not each transfer or implementation
僅供背景參考 CONTEXT_ONLYContext only
文件日期:2024-03-07 · 查核日期:2026-11-06T07:48:31.627Z
支持範圍:Local-government implementation coordination
限制:Meeting or plan is not project completion
顯示 3/9 筆台灣官方來源。Showing 3 of 9 Taiwan institutional sources.
本卡不宣稱整篇文章的單一法律狀態,也不是法律意見或合規判定。來源日期不是生效日。No aggregate legal conclusion, legal advice or compliance determination. A document date is not an effective date. 第 07 段/Section 07 → 完整來源鏈/Full evidence chain →
台灣傳導判讀
- 事件與本文範圍
- 承諾不等於收受或執行。
- 制度狀態
- 《氣候變遷因應法》與風險評估準則在其政府權責範圍內屬現行法規;國家計畫及金融政策是政策脈絡;FSC新聞公告不能代替正式修正條文;永續經濟活動及TNFD指引屬自願參考。
- 台灣路徑與有權角色
- 第 07 段說明本文的市場傳導、對象與可執行職能。前往第 07 段 →
- 不得推論
- 本篇禁止推論:同一筆承諾出現在財務、採購與永續資料中,不表示資金已到達受益者,亦不證明成果已獲認可。
全球原始分析、台灣證據鏈與本站編輯解讀分別標示;下方來源可供核對,並不代表來源機構認可本篇結論。
Taiwan legal and sourcing boundary
Event and scope: A commitment does not establish receipt or implementation.
Taiwan state: The Climate Change Response Act and risk-assessment regulation bind competent authorities within scope; national plans and green-finance programmes provide policy context. An FSC news notice does not replace operative amended text. Activity and TNFD guidance remain voluntary references.
Market transmission: Cross-border fund and buyer information requests flow through contracts, lending and issuer disclosure processes to Taiwan manufacturers, financial institutions and suppliers as evidence demands on receipt, use, site and outcome. Read Section 07 →
Do not infer: Prohibited inference for this edition: A commitment appearing in finance, procurement and sustainability records does not prove recipient access or institutional recognition of an outcome.
Who Can Prove Delivery? Taiwan Climate and Nature Finance Across Commitment, Access and Implementation
How do global climate and nature finance commitments reach Taiwan? This independent interpretation separates approval, disbursement, receipt, implementation and outcome, and identifies the evidence and responsible roles needed before claims are disclosed.
重點摘要
Executive Summary / Lead全球 EIS-027 提出的問題不是資金是否曾被宣布,而是誰能證明資金已由有權機構核准、實際撥付、由指定主體收受並用於預定工作。UNFCCC 的全球氣候融資估算、UNEP 的調適資金缺口與損失損害基金申請、CBD COP17 的承諾,以及 IUCN 對非國家行動能見度的評論,分屬不同母體與權限,不能相加為同一條交付鏈。[1–7] 台灣版檢視本地調適治理、金融授信、上市櫃揭露與自然風險資料如何要求不同的交付證據。本文是 SNN.TW 獨立台灣市場解讀,全球正典是制度脈絡起點,並非本地法規的替代來源。
Global EIS-027 asks who can demonstrate that financing moved from an announced commitment to authorised approval, actual transfer, receipt by a named actor and implementation for an intended purpose. The UNFCCC aggregate, UNEP adaptation gap and loss-and-damage requests, CBD COP17 pledges and IUCN's observation about non-state visibility belong to different populations and authorities; they cannot be added into one delivery chain. [1–7] This SNN.TW edition independently examines how Taiwan adaptation governance, financial due diligence, issuer disclosures and location-based nature evidence create distinct questions about delivery. The global canonical is the analytical starting point, not the source of Taiwan legal duties.
企業與產業背景
Company & Industry Context台灣《氣候變遷因應法》第 17 至 20 條建立中央領域調適方案、國家計畫與地方執行方案的政府權責。[10] 2023 至 2026 年國家調適計畫列有七大領域、126 項工作與預定經費;核定計畫的存在不等於各項預算已撥至執行者,也不等於工程或生態成果已驗收。[11–12] 金管會綠色金融政策與永續經濟活動認定參考指引則提供金融機構和企業評估用途與活動的制度脈絡。[14–15] 這些台灣來源的法律位階與適用對象不同,不能把政策目標、參考指引、授信契約與上市櫃公司的法定揭露寫成同一項義務。跨境資金或供應鏈要求另須回到實際合約與交易主體。
Taiwan's Climate Change Response Act assigns adaptation planning and reporting responsibilities to competent central and local authorities in Articles 17–20. [10] The 2023–2026 National Adaptation Action Plan identifies seven sectors, 126 projects and an earmarked investment programme. Approval of the plan establishes neither disbursement to each implementing actor nor acceptance of each engineering or ecological outcome. [11–12] FSC green-finance policies and its second-edition sustainable-activity reference guidance offer a different institutional context for lenders and firms. [14–15] These sources differ in legal status and addressees. A national policy target, optional reference method, lending contract and statutory issuer disclosure must not be presented as one obligation. Cross-border buyer requests depend on the actual contract and responsible entities.
挑戰與重要性
Challenge / Why It Matters全球數字最容易造成第一個誤讀。UNFCCC 第七次雙年評估的約 1.9 兆美元年平均氣候融資涵蓋多種公私及境內外投資;其百億美元目標進度報告有另一個資金母體。[1–2,8–9] UNEP 報告中的 2024 年國際公共調適流量與 2035 年年度需求估算,年份與衡量問題也不同。[3] 損失損害基金首輪申請約 28 億美元、初始可用額度約 3.42 億美元,前者是需求申請,後者是資金包絡,並非已核准或已撥付金額。[3–4] CBD COP17 公布的資金承諾同樣不是受益方收款證明。[5] 台灣採購方與授信人若把全球統計帶入本地專案,必須先區分承諾、核准、授信簽約、撥款、收受、支出及成果觀測的資料母體、日期與幣別。
The first error is to collapse aggregate figures. The UNFCCC Seventh Biennial Assessment estimates average annual global climate finance of about US$1.9 trillion across public and private, domestic and international investment; its separate report on the USD 100 billion goal examines another population. [1–2,8–9] UNEP's international public adaptation flows for 2024 and annual needs estimate for 2035 address different years and purposes. [3] In the Fund for responding to Loss and Damage's first round, approximately US$2.8 billion of requests faced an initial US$342 million envelope. Requested support and available envelope are neither approved awards nor recipient disbursements. [3–4] COP17 financing pledges similarly do not establish cash receipt or verified biodiversity results. [5] A Taiwan buyer or lender referring to these signals must identify the population, currency, period and state of each local claim: commitment, approval, signed finance, transfer, receipt, expenditure or observed result.
行動、方案與執行
Action / Solution / Implementation對台灣企業,最實用的做法是按權責建立「交付狀態簿」,而不是一張只寫已投入金額的總表。董事會或有權預算單位保存決議、金額上限及附帶條件;財務部門連結核准、合約、撥付通知、銀行收款及會計憑證,標出付款方、中介、最終收受者及時點。採購與專案單位保留招標、採購單、供應商交付、施工或保育活動的驗收文件;永續部門把場址、基線、活動與監測資料相連,但不能自行把執行紀錄升格為減災或生物多樣性成果。內部稽核可按版本抽查中途變更、退回、重新分配及未完成條件;確信人員的判斷仍取決於委任範圍與證據充分性。每個節點都應記錄來源機構、法律主體、日期、權限、金額狀態、使用範圍及下一節點的關聯依據。若同一資金經過基金、銀行、地方機關與承包商,應保留每次移轉的識別,不以共同專案名稱推定資金已到達最終場址。
For a Taiwan enterprise, a delivery-state ledger is more useful than a table headed simply “funding invested.” A board or authorised budget office retains the resolution, ceiling and conditions. Finance links the approval, instrument, transfer instruction, bank receipt and accounting voucher, distinguishing payer, intermediary, intended recipient and date. Procurement and project teams retain tender, purchase order, supplier delivery, acceptance and restoration or construction activity records. Sustainability teams connect the site, baseline, activity and monitoring records, but cannot convert an implementation record into an adaptation or biodiversity outcome by assertion. Internal audit can sample versions, delayed conditions, returned funds, reallocations and incomplete work. An assurance provider's conclusion remains governed by engagement scope and evidence sufficiency. Each transition needs an attributable institution, legal entity, decision authority, date, amount state, purpose and evidence connecting it to the next event. Where a fund, bank, local government and contractor share a project name, that common label alone cannot prove that resources reached the final site.
證據、成果與影響
Evidence / Results / Impact台灣調適計畫、氣候風險評估作業準則與地方方案的制度證據,可確認政府規劃、風險評估及報告權責。[10–13,18] 企業端若受金管會永續揭露分階段規則約束,需另查正式法規、資本額及適用年度;2026 年金管會新聞公告只能支持該機關的政策說明,不能代替正式法源。[16] 林業保育署的台灣 TNFD 在地操作指引可支援場址及自然依賴的自願分析,不能證明個別復育計畫已有驗證成果。[17] 台灣金融機構對綠色授信、永續績效連結授信及活動認定的判斷,還須檢視資金用途、契約條件和自身授信程序。[14–15] 全球 IUCN 對非國家貢獻在 CBD 綜整中能見度的看法,僅是 IUCN 的機構評估,不是 CBD 承認所有貢獻均遭排除或已獨立核驗。[6]
Taiwan's adaptation statute, risk-assessment regulation and local-government implementation material support claims about government planning, risk evaluation and reporting responsibilities. [10–13,18] If an issuer falls within phased sustainability disclosure requirements, its applicable accounting year, capital threshold and operative legal instruments must be checked separately. The 2026 FSC news notice supports the regulator's explanation, but cannot substitute for the amended rule itself. [16] The Forestry and Nature Conservation Agency's Taiwan TNFD implementation guide supports voluntary, site-based analysis of nature dependencies and risks; it does not verify the outcome of a particular restoration project. [17] A lender evaluating green or sustainability-linked finance still needs the actual use of proceeds, contractual conditions and its own credit process. [14–15] IUCN's assessment that non-state contributions were largely missing from the CBD global synthesis is attributable to IUCN. It is neither a CBD finding that every contribution was excluded nor independent validation of any underlying contribution. [6]
產業與制度意涵
Industry & Institutional Implications市場傳導有三條具體路徑。第一,台灣製造商與設施供應商參與國際調適或自然專案時,外國採購方可能要求核對預付款、設備交貨、驗收及受益場址,這是契約要求而非一律的台灣法定揭露。第二,本地銀行、投信與保險業在綠色或轉型融資中,會把用途、收款、績效條件及監測資料納入授信與投資審查;金融政策鼓勵並不等於每筆貸款獲准。[14–15] 第三,上市櫃企業可能需在適用年度的年報或永續報告中說明氣候風險與投入,但報導金額、支出及環境成效不可互代。[16] 對海外買方而言,台灣法律狀態卡應把已生效法規、政策公告、參考指引和契約要求分開,避免將 COP17 路徑或 UNFCCC 財務估算誤寫成台灣企業義務。
Three pathways matter to Taiwan. First, manufacturers and facility suppliers in international adaptation or nature projects may encounter overseas buyer requests for advance-payment, delivery, acceptance and beneficiary-site evidence. That is a contractual information demand, not a universal Taiwan statutory disclosure duty. Second, domestic banks, asset managers and insurers may consider use of proceeds, recipient access, performance conditions and monitoring during credit or investment review; a green-finance policy does not approve an individual facility. [14–15] Third, listed issuers may have to explain climate risk and resource commitments in an annual or sustainability report in the applicable period, while reported budget, actual spend and environmental effect remain distinct. [16] An international procurer should read Taiwan legal-state metadata as separate binding rules, announcements, voluntary guidance and contract requests. COP17 outcomes and UNFCCC estimates do not automatically become duties for a Taiwan supplier.
SNN 編輯與揭露前證據基礎設施觀點
SNN Editorial / Pre-Disclosure Evidence Infrastructure Perspective全球 UNFCCC、UNEP 與 CBD 在 2026 年更新的融資及生物多樣性制度報告,分別調整了對資金流量、調適缺口和承諾的描述;這些全球制度變動經由跨境金融審查、採購合約與供應鏈資料要求傳導,使台灣製造、金融與上市櫃企業在專案收款、用途及揭露前面臨更細的證據區分。[1–5] 這是可能的市場傳導,不代表國際報告直接在台灣創設法定義務。台灣《氣候變遷因應法》的政府調適責任、金管會公告與自願參考指引仍須依各自狀態判斷。[10,15–16] SNN Editorial / 揭露前證據基礎設施(Pre-Disclosure Evidence Infrastructure)觀點的事實邊界:承諾不等於收受或執行。董事會及財務部門應在簽約或撥款前核對決議、合約與付款條件,記錄核准者、收受者及版本。採購與專案單位應在每次交付及驗收時保存訂單、收據、場址與工作紀錄,對照資金用途與完成範圍。永續及內部稽核部門應在年報或對外宣稱前查核監測基準、結果、修訂及未完成事項,將可觀測成果與單純活動分開。確信與授信機構只在授權範圍內判斷可採用性,不由資料庫替代其結論。本篇禁止推論:同一筆承諾出現在財務、採購與永續資料中,不表示資金已到達受益者,亦不證明成果已獲認可。
xt entry area (settable) The UNFCCC, UNEP and CBD updated global institutional reporting in 2026 on finance flows, adaptation gaps and biodiversity commitments. Those global institutional changes can transmit through cross-border financial review, procurement contracts and supply-chain data requests, creating more granular evidence demands for Taiwan manufacturers, financiers and listed companies concerning project receipt, use and pre-disclosure claims. [1–5] This is a conditional market transmission, not a claim that international reports themselves create Taiwan statutory duties. The government adaptation responsibilities in Taiwan's Climate Change Response Act, FSC announcements and voluntary reference guidance retain their respective legal states. [10,15–16] SNN Editorial / Pre-Disclosure Evidence Infrastructure Perspective is an independent editorial interpretation. Its fact boundary: A commitment does not establish receipt or implementation. Before contracting or disbursement, the board and finance team should reconcile the resolution, agreement and payment conditions, recording the approver, recipient and version. At each delivery and acceptance, procurement and project teams should retain purchase orders, receipts, site identifiers and work records, comparing them with the stated use of funds and completed scope. Before an annual report or public outcome claim, sustainability and internal-audit teams should test the monitoring baseline, results, revisions and incomplete items, separating observed effects from activities. Assurance providers and lenders decide admissibility only within their authorised mandates; a shared database does not replace their judgment. Prohibited inference for this edition: A commitment appearing in finance, procurement and sustainability records does not prove recipient access or institutional recognition of an outcome.
未來展望
Future Outlook下一步不是替所有資金工具建立單一路徑,而是讓各機構在其授權目的下追問:哪一版承諾被核准,誰實際收款,哪項工作由誰完成,哪些結果可獨立觀測,哪些貢獻進入正式審查。貸款、補助、保證、自然市場工具的法律及現金流結構各異;未撥款、退回與改案也應留下歷史。若台灣企業或金融機構準備對外說明交付,須以本地適用法規與實際契約核對,保留可追溯的來源、時間和權限邊界。可重建的歷史只是供有權審查者判讀的基礎,不是自動取得資金、合規、確信或環境成果的保證。
The next question is not whether every instrument can be forced into a single universal workflow. It is whether an authorised reviewer can find which version of a commitment was approved, who received the funds, what work a responsible actor completed, which results were independently observed and which contribution entered a formal review. Loans, grants, guarantees and nature-market instruments have different legal structures and cash-flow states. Non-disbursement, returns, reallocations and redesign should remain in the history as well. Before making a delivery claim, a Taiwan enterprise or financial institution should check the applicable domestic instrument and actual contract, then retain attributable sources, dates and limits of authority. A reconstructable history enables examination by competent institutions; it does not guarantee funding access, compliance, assurance, acceptance or environmental outcomes.
來源、證據鏈與責任編輯
來源媒體:Sustainability News Network Global · 原文作者:Anderson Yu · 原文發布:
原始出版
外部論述與制度來源
以下外部公告、法規、研究或新聞用於支撐本文論述,並與原始出版分開呈現。
- Official source 1UNFCCCSeventh Biennial Assessment and Overview of Climate Finance Flows ↗出版日期 2026-11-03 · 查核時間 2026-11-06 15:48 (UTC+8)
Global finance estimate and measurement boundaries
State: CONTEXT_ONLY · Jurisdiction: Global
Support scope: Global finance estimate and measurement boundaries
Limitation: Aggregate is not recipient access
- Official source 2UNFCCCThird report on progress towards the USD 100 billion goal ↗出版日期 2026-11-03 · 查核時間 2026-11-06 15:48 (UTC+8)
Separate international finance population
State: CONTEXT_ONLY · Jurisdiction: Global
Support scope: Separate international finance population
Limitation: Not additive to global investment
- Official source 3UNEPAdaptation Gap Report 2026: Ready? Not ↗出版日期 2026-11-04 · 查核時間 2026-11-06 15:48 (UTC+8)
2024 adaptation flows, 2035 needs and barriers
State: CONTEXT_ONLY · Jurisdiction: Global
Support scope: 2024 adaptation flows, 2035 needs and barriers
Limitation: Different years and measures; not Taiwan allocation
- Official source 4UNEPAs world heads for overshoot of 1.5°C, adaptation is too slow ↗出版日期 2026-11-04 · 查核時間 2026-11-06 15:48 (UTC+8)
Loss-and-damage requests and initial envelope
State: CONTEXT_ONLY · Jurisdiction: Global
Support scope: Loss-and-damage requests and initial envelope
Limitation: Request and envelope are not approval or disbursement
- Official source 5CBD SecretariatUN Biodiversity Conference charts Yerevan Pathway ↗出版日期 2026-10-31 · 查核時間 2026-11-06 15:48 (UTC+8)
COP17 decisions and pledge announcements
State: CONTEXT_ONLY · Jurisdiction: Global
Support scope: COP17 decisions and pledge announcements
Limitation: Pledge is not transfer or outcome
- Official source 6IUCNIUCN closing statement: 17th UN Biodiversity Conference ↗出版日期 2026-11-01 · 查核時間 2026-11-06 15:48 (UTC+8)
Attributed non-state actor visibility assessment
State: CONTEXT_ONLY · Jurisdiction: Global
Support scope: Attributed non-state actor visibility assessment
Limitation: IUCN view is not CBD determination
- Official source 7UNEP Finance InitiativeThe Yerevan Pathway: what does it mean for UNEP FI members? ↗出版日期 2026-11-05 · 查核時間 2026-11-06 15:48 (UTC+8)
Private nature finance and public obligation distinction
State: CONTEXT_ONLY · Jurisdiction: Global
Support scope: Private nature finance and public obligation distinction
Limitation: Analysis is not verified impact
- Official source 8UNFCCCSeventh biennial assessment: Technical Report ↗出版日期 2026-10-27 · 查核時間 2026-11-06 15:48 (UTC+8)
Methods and definitions in climate finance data
State: CONTEXT_ONLY · Jurisdiction: Global
Support scope: Methods and definitions in climate finance data
Limitation: Same assessment lineage; no Taiwan allocation
- Official source 9UNFCCCSeventh biennial assessment: Executive Summary ↗出版日期 2026-10-27 · 查核時間 2026-11-06 15:48 (UTC+8)
Summary findings and recommendations
State: CONTEXT_ONLY · Jurisdiction: Global
Support scope: Summary findings and recommendations
Limitation: Same assessment, not independent corroboration
- Official source 10Taiwan Ministry of Environment氣候變遷因應法 Climate Change Response Act ↗出版日期 2023-02-15 · 查核時間 2026-11-06 15:48 (UTC+8)
Articles 17–20 allocate adaptation planning to competent authorities
State: CURRENT_BINDING_RULE · Jurisdiction: Taiwan
Support scope: Articles 17–20 allocate adaptation planning to competent authorities
Limitation: 正式法規;不使所有私人企業負同一政府計畫義務
- Official source 11Taiwan Ministry of EnvironmentNational Climate Change Adaptation Action Plan 2023–2026 approved ↗出版日期 2023-10-25 · 查核時間 2026-11-06 15:48 (UTC+8)
Seven sectors and 126 government projects
State: CONTEXT_ONLY · Jurisdiction: Taiwan
Support scope: Seven sectors and 126 government projects
Limitation: Earmarked budget is not each transfer or implementation
- Official source 12Taiwan Ministry of Environment環境部啟動地方氣候變遷調適執行方案 ↗出版日期 2024-03-07 · 查核時間 2026-11-06 15:48 (UTC+8)
Local-government implementation coordination
State: CONTEXT_ONLY · Jurisdiction: Taiwan
Support scope: Local-government implementation coordination
Limitation: Meeting or plan is not project completion
- Official source 13Taiwan Ministry of Environment氣候變遷風險評估作業準則 ↗出版日期 2025-07-16 · 查核時間 2026-11-06 15:48 (UTC+8)
Government climate risk assessment methods
State: CURRENT_BINDING_RULE · Jurisdiction: Taiwan
Support scope: Government climate risk assessment methods
Limitation: 正式法規;適用主管機關評估,不等於私人確信義務
- Official source 14Taiwan Financial Supervisory Commission綠色金融行動方案3.0 policy overview ↗出版日期 2022-09-26 · 查核時間 2026-11-06 15:48 (UTC+8)
Finance policy and data direction
State: CONTEXT_ONLY · Jurisdiction: Taiwan
Support scope: Finance policy and data direction
Limitation: Policy is not individual credit approval
- Official source 15Taiwan Financial Supervisory Commission永續經濟活動認定參考指引第二版 ↗出版日期 2024-12-31 · 查核時間 2026-11-06 15:48 (UTC+8)
Activity reference across industries
State: VOLUNTARY_USE · Jurisdiction: Taiwan
Support scope: Activity reference across industries
Limitation: Guidance does not certify outcomes or guarantee finance
- Official source 16Taiwan Financial Supervisory Commission為編製115年報所需,提醒第一階段上市櫃公司優先蒐集準備氣候相關資訊 ↗出版日期 2026-02-21 · 查核時間 2026-11-06 15:48 (UTC+8)
FSC phased issuer reporting notice
State: ANNOUNCED_CHANGE · Jurisdiction: Taiwan
Support scope: FSC phased issuer reporting notice
Limitation: 公告本身非正式修正法規;核對門檻與法源
- Official source 17Taiwan Forestry and Nature Conservation Agency臺灣TNFD在地操作指引 ↗出版日期 2026-08-31 · 查核時間 2026-11-06 15:48 (UTC+8)
Location-based nature risk guidance
State: VOLUNTARY_USE · Jurisdiction: Taiwan
Support scope: Location-based nature risk guidance
Limitation: Voluntary method, not statutory duty
- Official source 18Taiwan Ministry of Environment環境部修正發布氣候變遷因應法施行細則 ↗出版日期 2023-12-29 · 查核時間 2026-11-06 15:48 (UTC+8)
Adaptation reports and public information mechanism
State: CONTEXT_ONLY · Jurisdiction: Taiwan
Support scope: Adaptation reports and public information mechanism
Limitation: Release describes rules; operative text controls legal conclusions
主題中心:揭露前證據基礎設施